
“Credit Is a Tool, Not a Trap” Ex-Ramsey Personality Anthony O'Neal
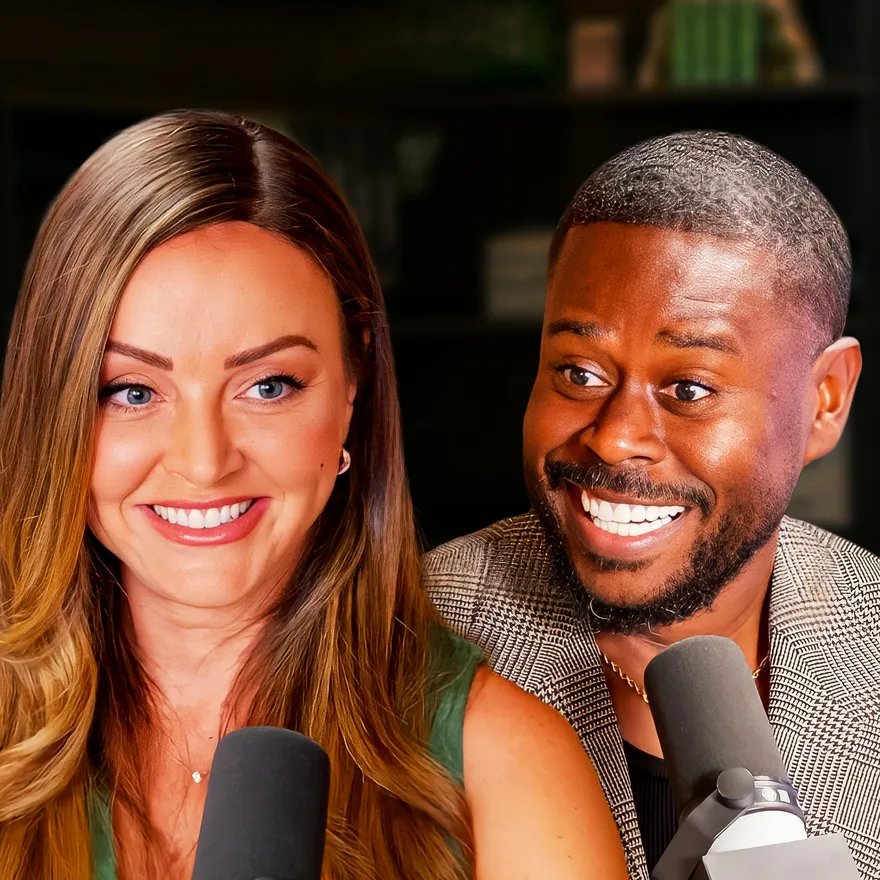
In this episode of Money Rehab with Nicole Lapin, former Dave Ramsey team member Anthony O'Neal discusses his evolution away from strict financial rules toward more flexible approaches that acknowledge modern economic realities. O'Neal shares how his views have shifted on topics like emergency funds, credit scores, and the psychology of sustainable wealth-building, explaining how rigid deprivation can lead to counterproductive financial behaviors.
The conversation explores the distinction between consumer debt and strategic leverage, particularly in real estate investing, and emphasizes defining personal financial freedom rather than chasing external benchmarks. Both Lapin and O'Neal advocate for financial education rooted in empathy rather than shame, acknowledging that mistakes often stem from lack of knowledge rather than character flaws. The episode offers practical guidance on balancing discipline with strategic indulgence while building long-term financial security.

This is a preview of the Shortform summary of the Oct 19, 2026 episode of the Money Rehab with Nicole Lapin
Sign up for Shortform to access the whole episode summary along with additional materials like counterarguments and context.
1-Page Summary
Evolution and Divergence From Dave Ramsey's Financial Philosophies
Nicole Lapin and Anthony O'Neal discuss O'Neal's shift from Dave Ramsey's rigid financial rules toward more flexible, empathetic guidance that acknowledges contemporary realities and diverse experiences.
Emergency Fund and Credit Score Philosophy
O'Neal credits the Ramsey method for his own financial freedom but recognizes significant gaps in the $1,000 starter emergency fund approach. When emergencies exceed this amount, he observes that people experience decision paralysis and may make poor choices under stress. O'Neal now advocates for at least one month's net income in savings, offering a 30-day buffer that allows thoughtful decision-making without drastic lifestyle disruption. His philosophy evolved through personal financial growth, higher education, and engagement with diverse audiences facing modern economic challenges.
On credit scores, O'Neal discusses how his initial adherence to Ramsey's stance of ignoring them led to real-world obstacles—his auto insurance doubled and he faced complications with rentals and leasing. He now takes a pragmatic approach, building credit without carrying debt through services that report utility payments and using credit cards like debit cards. This strategy dropped his insurance premium from $6,000 to $2,900 annually while maintaining his debt-averse values.
Respect Over Shame
O'Neal distances himself from harsh language like "stupid tax" to describe financial mistakes, agreeing with Lapin that shaming deepens trauma and hinders learning. He emphasizes that mistakes often stem from lack of education rather than character flaws, and stresses distinguishing between setbacks from uncontrollable circumstances versus deliberate decisions. For both educators, effective guidance balances tough love with forgiveness, focusing on equipping people with tools for growth rather than condemnation.
The Psychology of Sustainable Wealth-Building
Lapin and O'Neal explore how sustainable wealth-building roots itself in psychology, balancing discipline with strategic indulgence while avoiding excessive deprivation.
Deprivation and Binge Behaviors
Lapin describes how rigid self-denial creates psychological pressure that explodes into impulsive spending, likening it to strict dieting that leads to binging. O'Neal shares his experience losing 40 pounds through strict eating, only to spiral after indulging post-goal. He warns that while those with financial chaos histories may need strict abstinence initially, this approach isn't psychologically sustainable long-term.
Strategic Indulgences and Financial Maturity
Both agree that sustainable financial systems incorporate planned, measured indulgence. Lapin outlines a model: 70% of income for essentials, 15% for big-picture goals, and 15% for extras that prevent deprivation. She illustrates that when someone earns $70,000, has no consumer debt, a completed emergency fund, and maxed retirement accounts, a $28 lunch isn't irresponsible—it's sensible.
O'Neal emphasizes developing financial and emotional maturity before allowing regular indulgences. He shares his personal journey: after becoming debt-free, he indulged in a custom home, later a BMW, and years later a four-year-old Rolls Royce with cash—each indulgence proportional to his increasing financial security. Their conversation makes clear that true financial health requires maturity to balance restriction and pleasure, letting planned rewards reinforce rather than undermine discipline.
Strategic Use of Debt and Leverage
O'Neal and Lapin discuss the crucial distinction between consumer and investment debt, particularly in real estate wealth-building.
Consumer Versus Investment Debt
O'Neal emphasizes the freedom from consumer debt like car loans and credit cards, which deplete cash flow without returns. Lapin agrees that not all debt is equal—consumer debt drains resources while investment debt in appreciating assets creates positive leverage. She likens leverage to rate arbitrage: borrowing at lower rates to invest at higher returns builds wealth. O'Neal clarifies that consumer debt freedom is essential for entrepreneurs, as not having personal liabilities during lean periods protects family security.
Mortgages and Investment Properties
O'Neal explains his goal to pay off his primary residence for emotional security, while Lapin outlines the mathematical case for strategic mortgage management—investing surplus funds typically yields higher returns than rapid mortgage payoff. However, both stress that for people with housing trauma, psychological comfort can outweigh spreadsheet advantages.
For investment properties, O'Neal leverages mortgages and lets tenant rent cover debt service. He's never paid cash for properties, instead using financing to build equity passively. Both agree that strategic debt use for cashflow-positive, appreciating assets differs fundamentally from consumer debt that stifles progress.
Defining Personal Financial Freedom
O'Neal emphasizes that financial freedom is deeply personal and introduces the concept of a "freedom number"—the net worth or income level at which one can prioritize personal goals without exchanging time for money. His own freedom number is $15 million in liquid investment assets, allowing him to focus on family while passing principal to future generations. Lapin adds that clear personal definitions prevent endless shifting of financial goals based on outside influences.
Both caution against letting social media set financial ambitions. Lapin points out that platforms showcase aspirational lifestyles that tempt people to chase ever-escalating goals they never originally desired. O'Neal asserts that the most powerful wealth-building tool isn't income but "margin"—the difference between income and expenses. Preserving margin allows saving, investing, and weathering emergencies, fostering real financial freedom regardless of income level.
Empathetic and Respectful Financial Education
Lapin and O'Neal advocate for financial education rooted in empathy rather than shame. Lapin shares her experience growing up without formal financial education, noting this perspective normalizes financial missteps and acknowledges socioeconomic factors. O'Neal balances empathy for those impacted by uncontrollable events with accountability for poor decisions, remaining respectful while direct: he never calls anyone stupid but will say a decision wasn't wise.
Their willingness to share evolving philosophies and admit imperfections builds trust. Lapin notes how beautiful it is to discuss changed opinions, while O'Neal emphasizes he's constantly learning and evolving. They recognize that financial literacy must adapt to technological and economic changes, with diverse voices enhancing education. However, Lapin acknowledges risks of misinformation from uncredentialed creators, and O'Neal urges people to seek trustworthy sources rather than relying solely on social media.
1-Page Summary
Additional Materials
Counterarguments
- While a $1,000 emergency fund may be insufficient for some, it can still serve as a realistic and achievable first step for individuals with limited means, helping to build momentum and confidence in saving.
- Strict avoidance of all consumer debt may not be practical or necessary for everyone; responsible use of credit can provide flexibility, rewards, and opportunities for building credit history.
- The emphasis on building credit through utility payments and credit cards used as debit cards may not be accessible to all, particularly those with low or unstable incomes.
- The 70/15/15 budgeting model may not be feasible for individuals living in high-cost areas or with lower incomes, where essentials may consume a much larger portion of income.
- While avoiding shaming language is important, some individuals may respond positively to tough love or direct feedback, finding it motivating rather than harmful.
- The distinction between consumer and investment debt can be blurred; not all investment debt results in positive returns, and leveraging can increase risk, especially in volatile markets.
- Paying off a primary residence quickly may provide not only emotional security but also protection against market downturns or rising interest rates, which can be overlooked in favor of mathematical optimization.
- The concept of a "freedom number" may inadvertently encourage people to focus excessively on a specific financial target, potentially leading to dissatisfaction or neglect of other life priorities.
- While margin is important, increasing income (not just reducing expenses) can be a more effective strategy for some individuals to achieve financial goals.
- The call for empathy in financial education, while valuable, may risk downplaying the importance of personal responsibility and the consequences of repeated poor financial decisions.
- Not all financial advice from uncredentialed sources is necessarily harmful; some individuals without formal credentials may offer practical, experience-based insights that resonate with certain audiences.
Actionables
- you can set up a monthly “margin tracker” by creating a simple chart that records your income, essential expenses, and discretionary spending, then visually highlight your margin each month to see how much you’re freeing up for savings, investing, or emergencies—this helps you focus on growing your financial buffer and making intentional choices about indulgences.
- a practical way to balance empathy and accountability in your financial life is to keep a “decision journal” where you briefly note the context and reasoning behind major financial choices, then review it quarterly to distinguish between setbacks from uncontrollable events and those from personal decisions, helping you learn without self-shaming.
- you can define your personal “freedom number” by writing down what financial freedom means to you, listing the specific lifestyle, security, and goals you want, and then calculating the monthly income or net worth needed to support that vision—this keeps your goals anchored to your values rather than shifting with outside influences.
Get access to the context and additional materials
Evolution and Divergence From Dave Ramsey's Financial Philosophies
Nicole Lapin and Anthony O'Neal delve into O'Neal's shift from Dave Ramsey's rigid financial rules toward a more flexible, empathetic, and pragmatic financial guidance that acknowledges contemporary realities and diverse lived experiences.
Anthony O'neal's Change From $1,000 Emergency Fund to Larger Baseline Reflects Economic and Personal Shifts
O'Neal credits the Ramsey method and baby steps for his own financial freedom but recognizes gaps and challenges that arise for those following the $1,000 starter emergency fund. He observes that when an emergency exceeds the fund—such as an unexpected $5,000 expense—people often experience decision paralysis and may make poor choices, especially under stress. The minimal cushion can force desperate measures like borrowing or liquidating assets, rather than allowing strategic, composed responses.
O'Neal now advocates for a more robust safety net: at least one month’s net income in savings. This approach offers a 30-day emergency buffer, allowing individuals to maintain their basic living standards and granting them the space to make thoughtful decisions—consulting advisors or strategizing—without a drastic lifestyle disruption. He shares anecdotal evidence, such as a single mother who weathered job loss with her child’s daycare routine intact thanks to a larger financial cushion, highlighting the practical benefit of this approach.
O'Neal’s philosophy evolved through personal financial growth, higher education—gaining a bachelor’s, MBA, and pursuing a doctorate in finance—and broad engagement with audiences facing modern economic volatility. This deeper financial education and feedback from a diverse community, including many in minority groups, motivated him to adopt adaptable, context-aware financial advice instead of rigid one-size-fits-all rules.
Anthony O'neal's Transition From Rejecting To Accepting Credit Scores Shows Pragmatic Financial Engagement While Staying Debt-Averse
O'Neal discusses his initial adherence to Ramsey’s stance on ignoring credit scores and avoiding all consumer credit, which led to real-world financial obstacles. For example, lacking a credit score caused his auto insurance to double and complicated leasing or buying after a natural disaster, as landlords and dealerships pull credit scores. Experience revealed that, in the realities of modern finance, credit scores directly affect things like insurance premiums, rentals, and lending access—even for those without consumer debt.
O'Neal sought a strategic, debt-averse way to play the “credit score game” without compromising his values. He researched methods of building credit without carrying debt, such as using services to report utility payments and maintaining trade lines through companies like Kickoff, which add positive history for a nominal monthly fee. He uses an American Express card like a debit card—never spending more than he can immediately pay off, ensuring he pays zero interest while still earning rewards points. As a result of improving his credit score through these responsible practices, O'Neal saw his insurance premium drop by more than half—from $6,000 to $2,900 per year.
His approach reflects a pragmatic adaptation: acknowledging that maintaining a good credit score is necessary for participating in everyday financial systems, while still rejecting consumer debt and unnecessary credit lines.
Shift From Shame to Respect In Acknowledging Poor Financial Decisions, Recognizing Lack of Basic ...
Here’s what you’ll find in our full summary
Evolution and Divergence From Dave Ramsey's Financial Philosophies
Additional Materials
Counterarguments
- While a larger emergency fund provides more security, saving one month’s net income may be unrealistic for low-income individuals or those living paycheck to paycheck, potentially discouraging them from starting to save at all.
- Dave Ramsey’s rigid rules, such as the $1,000 emergency fund, are intentionally simple and accessible, making them easier for financial beginners to follow and less overwhelming than more nuanced advice.
- The focus on credit scores, even with responsible practices, may inadvertently encourage some individuals to engage with credit products they do not fully understand, increasing the risk of debt for those lacking financial discipline.
- Some argue that tough love and direct language, like “stupid tax,” can serve as a wake-up call and motivate behavioral change for certain personalities, rather than always being harmfu ...
Actionables
- you can create a personal financial flexibility checklist that helps you adapt your money decisions to changing life circumstances, such as job changes, family needs, or unexpected expenses, by listing possible scenarios and your planned responses for each (for example, if you lose income, which expenses will you pause or reduce first, and what resources can you tap into).
- a practical way to build a more empathetic and forgiving mindset around money mistakes is to keep a judgment-free money journal where you record financial missteps, note what you learned, and write a compassionate response to yourself as if you were advising a friend, helping you separate self-worth from financi ...
Get access to the context and additional materials
The Psychology of Sustainable Wealth-Building
Nicole Lapin and Anthony O'Neal discuss how sustainable wealth-building is rooted not just in numbers, but in psychology. Their conversation reveals that the healthiest financial journeys balance discipline with strategic indulgence, acknowledge the risks of excessive deprivation, and stress the need for financial maturity before introducing personal spending freedoms.
Excessive Financial Deprivation Can Trigger Binge Behaviors, Undermining Long-Term Progress
Lapin describes a familiar trap on the road to financial discipline: rigid self-denial leads to psychological pressure, which can explode into excessive, impulsive spending. She likens it to strict dieting—if she denies herself even a small treat like a Hershey’s kiss, she finds herself binging on a big piece of chocolate cake in the middle of the night. O’Neal recounts his own experience of losing 40 pounds through strict eating. He indulged with a couple of sweet cocktails after reaching his goal, only to immediately spiral into several more, proving that too much restraint without strategic indulgence can lead to loss of control.
O’Neal points out that those with histories of financial chaos may feel the need for strict abstinence, which is appropriate for a time, but warns that this approach can hinder long-term stability as it’s not psychologically sustainable. He notes: “I don’t think you can have peace and joy and freedom if you are in that deprivation state,” though he concedes a period of discomfort may be necessary to build healthy habits early on.
Strategic Indulgences Within Structured Spending Prevent Financial Derailment and Psychological Burnout From Excessive Restriction
Both agree that a sustainable financial system incorporates planned, measured indulgence. Lapin outlines a model: 70% of income goes to essentials, 15% to “end game” (big picture goals), and 15% to extras—small indulgences that prevent deprivation without derailing future wealth. She shares that when someone earns $70,000, has no consumer debt, a completed emergency fund, and is maxing out retirement accounts, indulging in a $28 lunch is not financially irresponsible; it’s a sensible small luxury that supports discipline and enjoyment.
Lapin distinguishes between planned moderation and excessive rebellion—having a latte or lunch out is symbolic, a way to satisfy human need for pleasure, versus bingeing on large, unplanned purchases. O’Neal stresses that Lapin’s approach does not mean “indulge and stay in the indulge,” but rather to build the muscle of discipline so that a planned treat does not undo months or years of progress. Small, intentional rewards help sustain motivation and prevent future lapses into old habits.
Develop Financial and Emotional Maturity Before Indulgences to Avoid Regression Into Old Spending Patterns
O’Neal emphasizes the necessity of developing financial and emotional maturity before allowing regular indulgences. He argues that debt-free individuals must continue exercising restraint to avoid over-indulgence, because the temptation ...
Here’s what you’ll find in our full summary
The Psychology of Sustainable Wealth-Building
Additional Materials
Clarifications
- In financial planning, the "end game" refers to long-term financial goals that define ultimate success, such as retirement, paying off a mortgage, or funding education. It focuses on building wealth and security over time rather than immediate spending. Planning for the end game helps prioritize saving and investing to achieve these major milestones. This concept ensures money is allocated toward future stability and desired life outcomes.
- "Maxing out retirement accounts" means contributing the maximum allowed amount to tax-advantaged savings plans like 401(k)s or IRAs each year. This strategy helps grow wealth efficiently by reducing taxable income and allowing investments to compound over time. It is important because it secures financial stability for retirement and leverages employer matches or tax benefits. Consistently maxing out these accounts accelerates long-term wealth-building.
- Binge spending triggered by deprivation is linked to the brain’s reward system, which craves relief from stress caused by strict self-denial. When deprived, dopamine levels drop, increasing cravings for immediate gratification through impulsive purchases. This behavior is a coping mechanism to temporarily reduce negative emotions like anxiety or frustration. Over time, it creates a cycle where deprivation leads to bingeing, undermining long-term financial goals.
- Planned moderation means intentionally setting aside a small portion of your budget for enjoyable, controlled spending that supports your overall financial goals. Excessive rebellion refers to impulsive, unplanned purchases that break your budget and undermine long-term progress. The key difference is control and alignment with your financial plan. Planned moderation sustains motivation, while excessive rebellion risks financial setbacks.
- Financial maturity means understanding how to manage money responsibly, including budgeting, saving, and investing wisely. Emotional maturity involves controlling impulses and making thoughtful decisions rather than reacting to immediate desires or stress. Together, they help prevent overspending and support consistent progress toward long-term financial goals. Developing both takes time, experience, and learning from past financial mistakes.
- An emergency fund provides a financial safety net for unexpected expenses like medical bills or car repairs. It prevents reliance on high-interest debt, which can derail financial progress. Having this fund reduces stress and allows for better decision-making during crises. It ensures long-term stability by protecting savings and investments from being prematurely spent.
- The 70/15/15 income allocation is a budgeting guideline designed to balance essential needs, long-term goals, and personal enjoyment. The 70% covers necessary expenses like housing, food, and bills to ensure financial stability. The 15% for "end game" focuses on savings and investments to build future wealth. The remaining 15% allows for dis ...
Actionables
- you can create a monthly mood-money journal to track how your emotions and stress levels change before, during, and after both disciplined saving periods and planned indulgences, helping you spot patterns and adjust your approach for better balance
- jot down a few sentences each week about your feelings toward money, noting any urges to splurge or feelings of deprivation, and review these notes monthly to see if your spending plan needs tweaks to prevent burnout or impulsive spending.
- a practical way to reinforce financial maturity is to set up a milestone-based reward system where you only unlock certain indulgences after achieving specific financial goals, like reaching a savings target or paying off a debt
- for example, decide that once you’ve saved three months’ worth of expenses, you’ll treat yourself to a favorite meal or small purchase, making indulgences directly tied to your progress and security. ...
Get access to the context and additional materials
Strategic Use of Debt and Leverage
Anthony O'Neal and Nicole Lapin discuss the crucial difference between consumer and investment debt and the nuanced decisions involved in leveraging debt, particularly in real estate, to build wealth and financial security.
Distinguishing Consumer Debt From Investment Debt Is Key To Building Wealth
Anthony O'Neal emphasizes the freedom that comes with avoiding consumer debt, such as car loans and credit cards, which deplete cash flow and offer no return. He recalls the relief of not having personal liabilities, which is vital in the unpredictable world of entrepreneurship. Not having monthly obligations for depreciating items ensures less financial stress during lean periods and allows him to focus on essentials and family.
Nicole Lapin agrees, stating not all debt is created equal. She underscores that consumer debt drains resources without building wealth. O'Neal illustrates this point by referencing a friend who financed a new Rolls Royce, calling it a poor financial decision since cars lose value instantly. In contrast, he buys a four-year-old, fully paid car, minimizing cash outflow and maximizing peace of mind.
In contrast, investment debt—like that used to acquire appreciating assets such as real estate or fund a business—can create positive leverage. O'Neal describes how carrying some business debt on assets that generate income is logical and strategic. Lapin likens leverage to rate arbitrage: borrowing money at a lower rate to invest in something with a higher return is how wealth is built. For example, if the mortgage on a rental property has a 7.2% rate but is expected to yield higher returns, the difference becomes profit and equity growth.
O'Neal is clear that while it feels great to be free from consumer debt, investment debt has a different, productive dynamic. He highlights that consumer debt freedom is especially essential for entrepreneurs and crisis prevention; if income suddenly drops, not having personal liabilities means one can shut down operations and protect personal finances and family security.
Mortgages: A Nuanced Debt Where Investing Surplus May Conflict With Housing Values
O'Neal explains that a mortgage is often the only personal debt he carries—and his goal is to pay off his primary residence for emotional and security reasons. Lapin outlines the mathematical case for strategic mortgage management: historically, investing spare cash in the market yields higher long-term returns than rapidly paying off a mortgage, especially given that the average housing market appreciation is 4–5%, lower than the stock market.
Lapin and O'Neal stress that this optimization only works for disciplined investors who actually allocate surplus funds to investments rather than increased consumption. She also notes that for people with a history of housing insecurity or trauma, the psychological comfort of a mortgage-free home can outweigh any spreadsheet advantage. Lapin recounts her childhood experience of foreclosure, which makes having a fully paid-off home a priceless source of peace of mind, regardless of what the numbers say.
O'Neal further remarks that life stages, family needs, and risk tolerance all shape personal mortgag ...
Here’s what you’ll find in our full summary
Strategic Use of Debt and Leverage
Additional Materials
Clarifications
- Positive leverage occurs when the return on an investment exceeds the cost of borrowing used to finance it. This means the investor earns more from the asset than they pay in interest, increasing overall profit. Investment debt amplifies gains by allowing control of a larger asset with less personal capital. However, it also increases risk if returns fall below borrowing costs.
- Rate arbitrage in borrowing and investing means borrowing money at a low interest rate and investing it in assets that generate a higher return. The difference between the borrowing cost and investment return creates profit. This strategy amplifies wealth growth but involves risk if returns fall below borrowing costs. Successful rate arbitrage requires careful calculation and risk management.
- Consumer debt is money borrowed to purchase goods or services that typically lose value or do not generate income, such as credit cards or car loans. Investment debt is borrowed to acquire assets expected to increase in value or produce income, like real estate or business loans. The key difference lies in whether the debt is used to build wealth or simply finance consumption. Investment debt can create financial growth through appreciation or cash flow, while consumer debt usually results in ongoing expenses without returns.
- Cars are considered depreciating assets because their value decreases over time due to wear, aging, and market factors. This decline means you lose money when selling a car compared to its purchase price. Financially, this reduces your net worth and cash flow since you cannot recover the full cost. Owning depreciating assets can strain finances if financed with debt, as payments continue while the asset loses value.
- When you buy an investment property with a mortgage, tenants' rent payments cover the monthly loan installments, reducing your out-of-pocket expenses. This means the property's income helps pay down the debt over time. As the mortgage balance decreases, your ownership equity in the property increases. This process allows you to build wealth passively through real estate.
- Historically, the average annual return of the stock market has been around 7-10%, which often exceeds typical mortgage interest rates. By investing surplus cash in the market, your money has the potential to grow faster than the interest saved by paying off a mortgage early. However, stock market returns are not guaranteed and can be volatile, while paying off a mortgage early provides a guaranteed, risk-free return equal to the mortgage interest rate. This strategy benefits disciplined investors who consistently invest rather than spend extra cash.
- Housing insecurity or trauma can create deep emotional stress and fear of losing shelter. This often leads individuals to prioritize owning a mortgage-free home for a sense of safety and control. The psychological comfort from stable housing can outweigh financial benefits of investing elsewhere. Such experiences shape risk tolerance and financial decisions around debt and homeownership.
- Mortgage strategies involve weighing the potential financial gains from investing surplus funds against the emotional comfort of owning a home outright. Financial math favors investing extra money to earn higher returns than mortgage interest rates, maximizing wealth over time. Emotional and security considerations prioritize peace of mind, reducing stress and providing stability, especially for those with past housing insecurity. Personal values, risk tolerance, and life circumstances ultimately guide the best approach for each individual.
- Cashflow-positive assets generate more income than their expenses, including debt payments. This surplus income can be reinvested or saved, accelerating wealth growth. In real estate, positive cash flow means rental income exceeds mortgage, taxes, and maintenance costs. Such assets reduce financial risk by covering their own costs and providing extra profit.
- Carrying business debt on income-generating assets is strategic because the asset produces cash flow that covers the debt payments, reducing financial strain. This leverage allows business owners to acquire more or higher-value assets than they could with cash alone. Interest on business debt is often tax-deductible, lowering the effective cost of borrowing. Properly managed, thi ...
Counterarguments
- While avoiding consumer debt is generally advisable, some forms of consumer debt (such as 0% financing offers or responsible credit card use with full monthly repayment) can provide benefits like building credit history or accessing rewards without significant financial risk.
- Purchasing used cars may minimize cash outflow, but newer vehicles can offer better fuel efficiency, lower maintenance costs, and improved safety features, potentially offsetting the higher initial depreciation.
- The assumption that investment debt always leads to wealth-building overlooks the risks of market downturns, vacancies, or unexpected expenses that can turn leveraged investments into financial liabilities.
- Rate arbitrage strategies depend on stable or rising markets; in periods of high interest rates or declining asset values, borrowing to invest can result in losses rather than profits.
- The psychological comfort of being debt-free is subjective and may not apply to everyone; some individuals may experience more stress from illiquidity or missed investment opportunities than from carrying manageable debt.
- Not all entrepreneurs or individuals have equal access to favorable loan terms or investment opportunities, making the strategic use of debt less universally applicable.
- The historical outperformance of the stock market over housing is not guaranteed in the fut ...
Get access to the context and additional materials
Defining Personal Financial Freedom Through Individual Freedom Numbers
Financial Freedom: Personal Values, Circumstances, and Lifestyle Outcomes
Anthony O’Neal emphasizes that financial freedom is deeply personal and should be tailored to each individual's values, circumstances, and desired lifestyle outcomes. He introduces the concept of a "freedom number," which is the net worth or income level at which one can prioritize personal goals without needing to exchange time for money. It is a personal benchmark that signifies when money is generating enough security and flexibility to make personal choices independent of payday pressures.
O’Neal shares that his own freedom number is currently $15 million in liquid investment assets—not including income from business ventures or rental properties. He explains that, once he reaches this target, he aims to focus on being a full-time husband, father, and grandfather. This freedom number allows him to envision modest family living, present engagement with his loved ones, and a legacy plan that passes the principal to future generations. O'Neal stresses that freedom numbers differ between individuals and should be adaptable as circumstances change, such as getting married or starting a family. Nicole Lapin adds that having a clear, personal definition prevents the endless shifting of financial goalposts based on outside influences.
Defining a Personal Freedom Number Is Key to Resisting Social Media Pressure
Both O’Neal and Lapin caution against letting social media set or continually raise one’s financial ambitions. Lapin points out that social platforms often showcase aspirational lifestyles, tempting people to stray from their own freedom visions and chase ever-escalating goals like yachts or multiple luxury homes—goals that may never have been desirable to them in the first place. This constant comparison leads to the so-called “endless-treadmill phenomenon.”
O’Neal underscores that discipline means maintaining commitment to one’s pre-defined freedom number, regardless of shifting trends online. He affirms the importance of unplugging occasionally and returning to one’s own priorities, reiterating, “What is our vision for our life?” and resisting the pressure to chase new goals simply because they are glamorized on Instagram or TikTok. Achi ...
Here’s what you’ll find in our full summary
Defining Personal Financial Freedom Through Individual Freedom Numbers
Additional Materials
Clarifications
- A "freedom number" is the amount of money you need to cover your living expenses indefinitely without working. To calculate it, estimate your annual expenses and multiply by 25 to 30, reflecting a safe withdrawal rate from investments. This figure represents the net worth that generates enough passive income to sustain your lifestyle. Adjust the number based on your risk tolerance, inflation expectations, and lifestyle changes.
- Liquid investment assets are funds or investments that can be quickly converted to cash without significant loss of value, such as stocks or bonds. They exclude income from business ventures or rental properties because those sources may be less predictable or harder to access immediately. This distinction helps measure financial freedom based on readily available resources. It ensures the freedom number reflects assets that provide immediate financial flexibility.
- Margin refers to the amount of money left over after all expenses are paid from your income. It represents your financial buffer or surplus that can be saved or invested. A positive margin means you spend less than you earn, enabling wealth growth and financial security. Maintaining margin helps avoid debt and prepares you for unexpected costs.
- The "endless-treadmill phenomenon" describes a cycle where people continuously chase new financial goals without feeling satisfied. Psychologically, it can cause stress, anxiety, and a sense of never achieving enough. Behaviorally, it leads to constant comparison with others and shifting priorities based on external influences. This cycle undermines long-term contentment and financial stability.
- Social media often highlights curated, idealized lifestyles that emphasize wealth and luxury. This exposure can lead individuals to compare themselves unfavorably, feeling pressure to match or exceed those standards. The constant stream of such content can distort personal financial priorities, making people chase unrealistic or unnecessary goals. This phenomenon can cause stress and dissatisfaction by shifting focus away from individual values and needs.
- Unplugging from social media helps reduce exposure to constant comparisons and unrealistic lifestyle portrayals that can distort financial goals. It allows individuals to focus on their own values and priorities without external pressure. This mental break supports clearer decision-making and prevents impulsive spending driven by envy or trends. Ultimately, it fosters discipline and commitment to a personal financial plan.
- Margin contributes to wealth-building by creating a consistent surplus that can be invested to generate passive income and compound growth. It provides a financial buffer, reducing reliance on debt and enabling opportunities during emergencies or market dips. Margin also disciplines spending habits, preventing lifestyle inflation as income rises. This sustainable approach accelerates net worth growth beyond mere saving.
- Adapting a free ...
Counterarguments
- The concept of a "freedom number" may oversimplify the complexities of financial security, as unforeseen life events (such as health crises or economic downturns) can rapidly alter financial needs, making any fixed number potentially unreliable.
- Focusing on a specific net worth or income target can inadvertently encourage a scarcity mindset or excessive fixation on financial metrics, potentially detracting from present enjoyment or non-financial aspects of well-being.
- The emphasis on individual definitions of financial freedom may overlook systemic barriers (such as wage stagnation, discrimination, or lack of access to financial education) that make achieving a "freedom number" unrealistic for many people.
- While margin (income minus expenses) is important, it may not be feasible for individuals living in high-cost areas or those with low or unstable incomes, making the advice less universally applica ...
Get access to the context and additional materials
Empathetic and Respectful Financial Education Versus Shame-Based Approaches
Nicole Lapin and Anthony O’Neal advocate for financial education rooted in empathy and respect rather than shame or judgment. Their discussion reveals that open, honest, and ongoing learning creates a more effective and trustworthy environment for financial growth.
Empathy and Accountability in Financial Education Drive More Effective Behavior Change Than Shame or Judgment
Both Lapin and O’Neal emphasize that recognizing diverse backgrounds helps reframe financial mistakes as gaps in knowledge, not as moral failings. Lapin shares her experiences growing up in an immigrant family without formal financial education, noting, “I can forgive my former self for what she did not know because she didn’t learn it at school. She didn’t learn it at home.” This perspective normalizes financial missteps and acknowledges socioeconomic factors that influence money management.
Anthony O’Neal mirrors this compassionate approach, balancing empathy for those impacted by uncontrollable life events with accountability for poor financial decisions. He states, “There are a group of people that life just happened to that was out of their control, and I have sympathy for those individuals. We also have another sector of people where we just made the bad money decisions. So I have to blame myself and look at myself in the mirror.” O’Neal underlines that while he remains steadfastly respectful, he is also direct: “I’ve never called no one stupid. I’ve never been disrespectful towards people, but I will say, hey, that was not a wise money move and you need to mature in that area.” This respectful directness keeps accountability intact without damaging dignity.
Both educators agree that shame is counterproductive. Lapin warns that shaming someone into budgeting or pursuing financial freedom rarely works and can be deeply harmful, citing her own struggles navigating money issues without family support.
Honest Vulnerability in Financial Evolution and Learning Shows Perfection Isn’t Needed For Teaching, Building Trust
Lapin and O’Neal’s willingness to share their evolving philosophies and admit imperfections makes them relatable and trustworthy. Lapin points out that she and O’Neal have publicly changed their opinions over time, highlighting how “it’s so beautiful and humbling to talk about how you’ve changed your opinions over the years because you’ve been really thoughtful about them.” Lapin references her own book, “Miss Independent,” noting that she wishes she had focused more on interdependence rather than just independence.
They also discuss how learning and teaching about finances is a continuous process, shaped by personal experience, education, and shifting circumstances. Lapin brings up her own setbacks, saying, “I just lost my home, my office, my everything. I didn’t have business insurance. Like, you know, at every step of the way.” Both agree that acknowledging these challenges reflects honesty and growth, letting others know that perfection is not a prerequisite for teaching or learning about money.
O’Neal adds that despite his expertise, he is constantly learning and evolving. “I’m always learning something. I’m always evolving. I can always do better with my money. So I will never make someone else feel bad.” This approach encourages ongoing growth rather than rigid adherence to previous ...
Here’s what you’ll find in our full summary
Empathetic and Respectful Financial Education Versus Shame-Based Approaches
Additional Materials
Counterarguments
- While empathy and respect are important, some individuals may respond better to more direct or tough-love approaches, which can serve as a wake-up call for necessary behavioral change.
- Emphasizing empathy and avoiding shame entirely may risk minimizing the seriousness of repeated poor financial decisions, potentially reducing motivation for some to change harmful habits.
- Accountability can sometimes require uncomfortable conversations or interventions that may be perceived as shaming, but are intended to prompt reflection and change.
- Focusing on socioeconomic factors and knowledge gaps may inadvertently downplay the role of personal responsibility in financial outcomes.
- The call for diverse voices in financial education is valuable, but it can also lead to conflicting advice, making it harder for learners to discern the most effective strategies.
- The emphasis on ongoing learning and admitting imperfection, while foster ...
Actionables
- you can start a personal money reflection journal where you write down not just your financial decisions, but also the emotions, circumstances, and outside factors that influenced them, helping you spot patterns without self-judgment and encouraging empathy for your own journey.
- a practical way to foster ongoing, honest financial learning is to set a recurring monthly reminder to review one new financial topic or tool (like a budgeting app, a new payment method, or a recent economic change), then jot down what you learned and how it might affect your choices, keeping your knowledge current and ad ...
Get access to the context and additional materials

 1-Page Summary
- Evolution and Divergence From Dave Ramsey's Financial Philosophies
- The Psychology of Sustainable Wealth-Building
- Strategic Use of Debt and Leverage
- Defining Personal Financial Freedom Through Individual Freedom Numbers
- Empathetic and Respectful Financial Education Versus Shame-Based Approaches
Create Summaries for anything on the web
Download the Shortform Chrome extension for your browser