
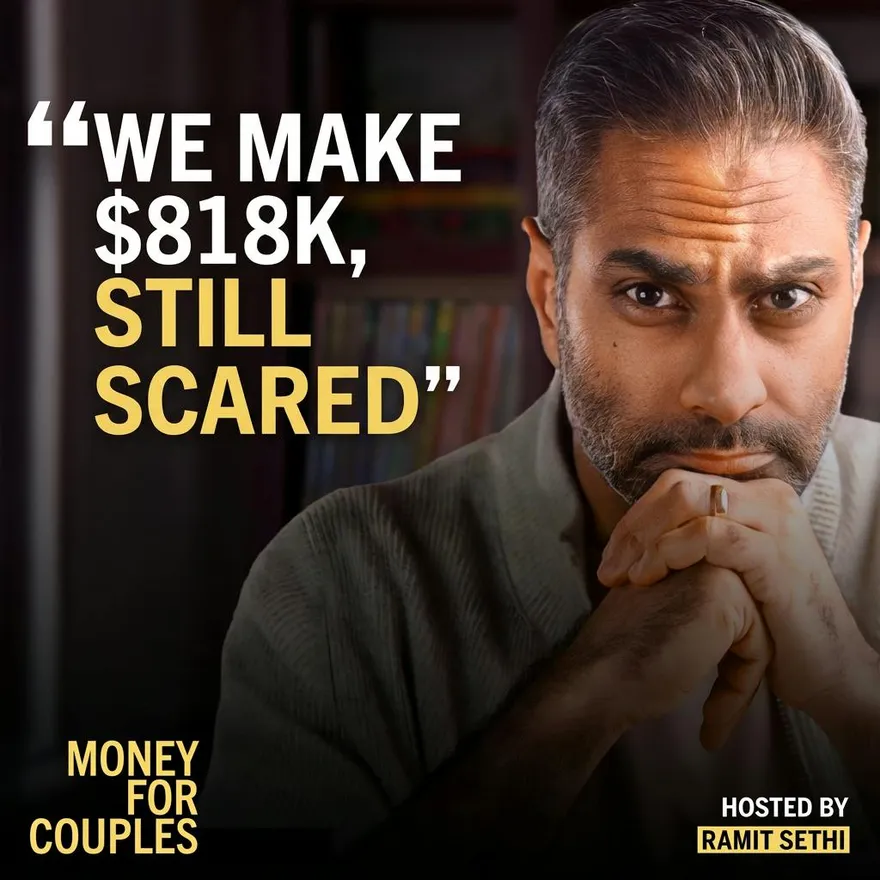
284. "We’re worth $1.8M, but I feel guilty buying a $78 jacket”
In this episode of I Will Teach You To Be Rich, Ramit Sethi examines Laura and Jason's journey toward early retirement. Despite a net worth of $1.8 million and a combined annual income over $800,000, Laura experiences anxiety about spending even $78 on a jacket. Sethi explores how their strong financial position supports multiple viable retirement scenarios—retiring as early as 45—yet persistent worry prevents them from fully enjoying their wealth.
The conversation reveals how childhood experiences and psychological patterns shape financial behavior regardless of net worth. Sethi discusses the couple's contrasting money philosophies, their 50-50 expense split despite income disparity, and Laura's limited financial knowledge beyond account balances. He provides practical guidance on creating worry-free spending thresholds, simulating retirement logistics, and building financial literacy within their partnership. The episode demonstrates that achieving financial security requires addressing both the mathematical and emotional dimensions of money.

This is a preview of the Shortform summary of the Oct 27, 2026 episode of the I Will Teach You To Be Rich
Sign up for Shortform to access the whole episode summary along with additional materials like counterarguments and context.
1-Page Summary
Early Retirement Planning and Financial Viability
Ramit Sethi examines Laura and Jason's path to early retirement, revealing how their exceptional financial position supports multiple retirement scenarios—despite persistent anxiety about money.
Strong Financial Foundation Despite Misjudged Income
Laura and Jason, both 38, earn a combined $818,820 annually with a net worth of $1.857 million. Their fixed costs are just 41% of net income, they invest 54% monthly ($22,000), and maintain minimal savings at 2% due to a robust emergency fund. Despite these impressive numbers, Laura had significantly underestimated their household income, believing it was around $400,000-$450,000 rather than double that amount.
Facet's analysis prepared three viable retirement scenarios: retiring at 45 with downsized lifestyle and $18,000 monthly spending; retiring at 47 after moving to Las Vegas with $25,000 monthly spending; or retiring at 55 while maintaining their current lifestyle with $32,000 monthly spending. All three scenarios project substantial net worth by age 95, demonstrating the couple's financial flexibility.
Lifestyle Choices, Not Finances, Determine Retirement Timing
Jason notes that retiring as early as 42 is feasible, particularly if healthcare is secured through his employer. Both Laura and Jason lean toward retiring at 45, prioritizing time together over accumulating more wealth. They're willing to downsize, travel in a van, and reduce their lifestyle significantly—moving from $6,000 in current guilt-free spending to $18,000-$21,000 in retirement. Their triplex rental property provides additional security through guaranteed cash flow.
Despite spending five times their intended $1,000 monthly guilt-free budget—reaching $5,764 recently—they remain well under the recommended 20-35% range for discretionary spending, highlighting considerable capacity for increased enjoyment without threatening long-term security.
Money Psychology and Emotional Blocks
Laura and Jason's story illustrates how emotional blocks about money persist regardless of net worth, revealing that financial security is as much psychological as mathematical.
Childhood Loss Shapes Laura's Financial Anxiety
Laura's money anxieties trace back to her family losing their house during the 2008 financial crisis. Her father's regret over not affording her college—which he named as one of his biggest regrets even while dying—planted deep beliefs that financial failure represents personal shortcoming. This manifests as trauma-level anxiety about spending: Laura cried over her first home offer and threw up after buying her first car. Even a $78 jean jacket triggers fears about jeopardizing retirement.
Wealth Accumulation Doesn't Resolve Deep-Seated Anxiety
Ramit observes that despite $1.8 million in net worth, Laura and Jason never truly feel safe. Laura admits to restlessness at night, endlessly worrying about whether early retirement is possible or if major purchases can be justified. The couple shifts worries from savings to market fluctuations to healthcare costs, creating a perpetual cycle of anxiety unsolvable by accumulation alone. When Ramit validated their financial plans, Laura teared up—Jason's years of reassurance hadn't helped, but minimal outside confirmation did.
Contrasting Money Views Create Dynamic Tension
Jason tends toward financial optimism, constructing models and running numbers, while Laura acts as the skeptical counterweight. Ramit notes this dynamic leaves Laura stuck as the naysayer, barred from excitement about spending. He encourages them to create a supportive financial culture together where excitement and shared guidelines replace role-based policing, emphasizing that true security requires intentionally rewiring the psychological relationship each person has with money.
Couple Communication and Relationship Dynamics Around Money
Financial decisions highlight deep dynamics in Laura and Jason's relationship, shaped by different earnings, spending habits, and philosophies.
50-50 Split Creates Burden Despite Income Disparity
Laura and Jason handle finances separately, splitting joint expenses 50-50 despite Jason earning significantly more. While Jason covers major outlays like down payments, the recurring even split feels unfair to Laura given her lower income. The couple lacks a structured or unified financial system—their budgeting tends to be informal, with Laura admitting she sometimes sets budget numbers based "on nothing other than vibes."
Opposing Spending Philosophies Clash
Laura views frivolous spending as a moral failing and meticulously justifies expenses before buying, while Jason enjoys spending within their means and acts more impulsively. Laura's hesitation to buy the $78 jean jacket—delaying for months despite loving it—exemplifies her financial self-protection. Jason was unaware her reluctance was financial, thinking she simply hadn't liked it. This lack of agreed thresholds, guidelines, or shared values results in ongoing confusion and negotiation about what's reasonable to spend.
Income Gap Undermines Laura's Financial Confidence
The income disparity means Laura feels less confident proposing or defending financial decisions, often deferring to Jason's judgment and financial optimism. She wishes she had stronger financial knowledge and assurance to propose realistic budgets, but lacking shared language around money goals sometimes leaves her feeling uncertain rather than empowered in their financial partnership.
Financial Knowledge Gaps and Building Money Competence
Laura's Limited Understanding Beyond Account Balances
Laura openly admits that while she knows their investment balances and net worth, she doesn't grasp deeper mechanics like tax implications or how to execute retirement withdrawals confidently. Her knowledge is mostly limited to account totals and spreadsheet lines. The couple's completion of a Conscious Spending Plan using Monarch software was transformative, giving Laura "complete transparency with all accounts" and shifting their conversations from abstract dreams to concrete planning.
Boosting Financial Literacy Key to Confident Planning
Ramit points out that understanding money mechanics—cash flow, taxes, and investment withdrawals—is key to overcoming financial overwhelm. He recommends Laura boost her financial knowledge by reading "I Will Teach You to Be Rich" and examining Jason's financial models together, establishing a shared financial language and framework. When a spouse takes genuine interest in financial flows and tools, it fosters greater competence and confidence.
Creating a "Worry-Free Spending Number"
Ramit introduces the concept of a "worry-free number"—a dollar threshold below which any spending requires no guilt or overanalysis. Laura's internal debate over the $78 jean jacket highlights her struggle with permission to spend. With a worry-free threshold, Laura can make decisions quickly and confidently, connecting positive experiences to spending rather than anxiety. Ramit even suggests a $100 challenge where Laura must buy something for herself and observe her emotional reactions, helping her internalize that minor expenses don't endanger their financial future.
Practical Retirement Transition Logistics
Beneath the financial planning lies practical and emotional hurdles in shifting from earning paychecks to drawing down investments.
Operational Uncertainty Fuels Anxiety
Despite ample savings, Laura is anxious about practical details like how they'll pay for groceries or travel once paychecks stop. Jason has started practicing by living only on his $4,300 monthly military pension, and Laura transfers most of her paycheck to savings, but the actual logistics still feel murky. Ramit recommends they simulate retirement before it arrives by establishing a joint account, automatically depositing Jason's pension, and simulating regular withdrawals. This rehearsal allows them to discover problems with years to spare.
Complex Finances Require Professional Guidance
Jason handles most finances, researching topics like Roth conversions, but managing rental properties, multiple mortgages, student loans, and investments feels overwhelming. Ramit urges them to hire a flat-fee financial advisor for specific retirement guidance and tax optimization, especially given their $818,000 annual income.
Supporting Laura's Mother Adds Complexity
Laura worries about her mother's retirement security, which complicates their own planning. Her mother lives on Social Security with limited means, and while Laura wants to ensure stable housing, they haven't explicitly discussed what support will look like. Ramit outlines several scenarios, noting that clarifying and settling these questions will ease Laura's anxiety about retiring.
1-Page Summary
Additional Materials
Counterarguments
- While Laura and Jason's high income and net worth provide significant financial security, their relatively low net worth compared to their income may indicate past overspending or missed investment opportunities, suggesting room for improved financial efficiency.
- The fact that Laura underestimated their household income by such a large margin raises concerns about their financial communication and awareness, which could undermine effective planning regardless of wealth.
- Relying on projections that extend to age 95 assumes stable market conditions and personal health, which may not account for unforeseen economic downturns, inflation, or major health events.
- Prioritizing lifestyle choices over continued wealth accumulation may be risky if unexpected expenses or economic changes occur, especially given the couple's anxiety about security.
- The triplex rental property, while providing cash flow, also introduces risks such as vacancies, maintenance costs, and potential declines in property value, which could impact their financial stability.
- Spending well below recommended discretionary levels may indicate an overly restrictive approach that could reduce quality of life, rather than a positive sign of financial discipline.
- Emotional blocks and anxiety about money, while real, may be better addressed through therapy or counseling rather than solely through financial education or planning.
- Splitting expenses 50-50 despite significant income disparity can perpetuate feelings of unfairness and resentment, and alternative arrangements (such as proportional contributions) might foster greater equity and partnership.
- Informal budgeting and reliance on intuition rather than data can lead to inefficiencies or missed opportunities for optimization, regardless of income level.
- The lack of shared financial values and thresholds may hinder relationship satisfaction and long-term financial harmony, suggesting the need for more structured communication and agreement.
- Focusing on increasing financial literacy is important, but it may not fully resolve deep-seated anxieties rooted in past trauma; psychological support may be equally necessary.
- Simulating retirement through practice withdrawals is helpful, but it may not fully prepare them for the emotional and logistical realities of no longer earning a paycheck.
- Hiring a financial advisor is prudent, but even professional advice cannot eliminate all uncertainties or guarantee outcomes, especially in complex financial situations.
- Supporting extended family members, such as Laura's mother, can significantly impact retirement plans and may require more explicit boundaries and planning than suggested.
Actionables
- You can create a monthly “lifestyle audit” by listing your top three non-financial priorities (like time with family, travel, or hobbies) and then reviewing your spending and schedule to see if your money and time actually support those priorities; adjust next month’s plans to better align with what matters most to you.
- A practical way to address emotional money blocks is to keep a “spending feelings journal” for two weeks, jotting down your emotions before and after each discretionary purchase, then reviewing patterns to identify triggers and brainstorm small, low-stakes purchases that help you practice feeling safe spending.
- You can set up a “financial confidence calendar” where, each week, you pick one small financial topic you feel unsure about (like how taxes work on investments or how to read a pension statement), spend 30 minutes learning about it, and write down one question to ask a knowledgeable friend or professional, building your understanding step by step.
Get access to the context and additional materials
Early Retirement Planning and Financial Viability
Ramit Sethi examines Laura and Jason's financial situation, exploring how their strong financial foundation supports early retirement—despite their anxieties—and the lifestyle decisions that drive their options.
Laura and Jason's Firm Financial Foundation Supports Multiple Retirement Scenarios Despite Their Anxiety
Laura and Jason, both 38, bring in a combined gross monthly income of $68,235 ($818,820 per year). Their net worth is $1.857 million, with $132,000 in cash, $542,000 in investments, and $1.89 million in property debt. Their net monthly income is $41,000. Fixed costs account for 41% of their net income, with their mortgage making up about 18% ($12,500/month). They consistently invest 54% of their income, close to maxing out retirement accounts, and put $22,000/month into various investment vehicles. Savings are just 2%, relying on an already robust emergency fund.
Despite these robust numbers, Laura has misjudged their resources, wrongly believing their gross household income was about $400,000–$450,000. The reality is double that, showcasing their exceptional earning power and capacity to plan for early retirement.
Facet’s analysis prepared three retirement scenarios, all feasible given Laura and Jason’s profile:
- Scenario One: Retire at 45, move into a rental unit, and travel by van. Spending would be about $18,000/month. Their net worth at age 95 would be $3M, factoring in helping Laura’s mom with housing. This scenario offers the earliest retirement but less flexibility in later spending.
- Scenario Two: Retire at 47, sell their current house, move to Las Vegas, and buy a home outright for $600,000. They’d keep the triplex rental (one unit for Laura’s mom), increasing retirement spending to nearly $25,000/month. Estimated net worth at 95 would be $4.69M. It entails two more years of work for greater spending flexibility.
- Scenario Three: Retire at 55, maintain current lifestyle and property setup, and support Laura’s mom. This allows for nearly $32,000 in monthly spending and a projected net worth of $9.4M at 95. The comfort of the largest nest egg comes at the cost of another decade of work.
Retiring At 42-45 Hinges on Lifestyle Choices, Not Finances
Jason points out that retiring as early as 42 is feasible, especially if healthcare is secured through his employer, erasing a potential $1,200 per person monthly expense until Medicare eligibility at 65. Laura and Jason both lean toward retiring at 45, prioritizing time together and shared experiences rather than amassing more wealth or chasing ultimate financial security.
Their readiness to scale down spending would see them going from $6,000 in current monthly guilt-free spending to $18,000–$21,000 in retirement (comfortably above a baseline minimum). They’re willing to sell their current single-family home, downsize, and live simply—possibly traveling in a van for a year or two, or trying life in places like San Diego, Nevada, or even Spain. ...
Here’s what you’ll find in our full summary
Early Retirement Planning and Financial Viability
Additional Materials
Clarifications
- Gross monthly income is the total amount earned before any taxes or deductions. Net monthly income is what remains after taxes, insurance, and other deductions are subtracted. Net income reflects the actual money available to spend or save. Understanding both helps in budgeting and financial planning.
- Property debt refers to the outstanding mortgage or loan balances secured by real estate owned. It reduces net worth because net worth equals total assets minus total liabilities, and property debt is a liability. Even if the property value is high, the debt owed against it lowers the overall net worth calculation. Managing property debt is crucial for accurate financial planning and assessing true wealth.
- Investing 54% of income means putting more than half of their earnings into savings and investments, accelerating wealth growth. "Maxing out retirement accounts" refers to contributing the maximum allowed by law to tax-advantaged accounts like 401(k)s or IRAs, which grow investments tax-free or tax-deferred. This strategy reduces taxable income now and builds a larger retirement fund over time. It is a key tactic for achieving early financial independence.
- "Guilt-free spending" is a budgeting strategy that allocates a specific amount of money for discretionary purchases without feeling guilty. It helps balance enjoyment and financial responsibility by setting clear limits on non-essential expenses. This approach prevents overspending while allowing personal satisfaction and flexibility. It supports long-term financial goals by controlling impulse buys and reducing stress over money.
- A triplex rental property generates income by renting out its three units to tenants. The rent collected typically covers the mortgage payments, property expenses, and can produce additional positive cash flow. Even with $1.89 million in debt, consistent rental income can exceed these costs, ensuring steady monthly cash flow. This income acts as a financial safety net by providing reliable funds regardless of other investments.
- Healthcare costs can be a major expense in early retirement since employer-sponsored insurance often ends when you leave your job. Medicare, a federal health insurance program, typically begins at age 65, covering most healthcare needs for seniors. Before Medicare eligibility, retirees must secure private insurance, which can be costly and unpredictable. Planning for these expenses is crucial to avoid financial strain during early retirement years.
- Fixed costs are regular, necessary expenses that do not change much month to month, like mortgage payments or insurance. Discretionary spending is money spent on non-essential items or experiences, such as dining out, shopping, or entertainment. Fixed costs must be paid to maintain basic living standards, while discretionary spending is flexible and can be adjusted based on budget or preferences. Managing both well is key to financial planning and achieving goals like early retirement.
- A guilt-free spending limit is a personal budget set to allow small, enjoyable purchases without financial stress. It helps maintain discipline by preventing overspending while supporting mental well-being. This limit encourages mindful spending, balancing enjoyment with long-term financial goals. It also reduces guilt or anxiety over discretionary expenses.
- Retiring earlier means fewer years to save and invest, requiring stricter budgeting and lifestyle adjustments. Later retirement allows more time to grow wealth and build a larger nest egg, increasing spending flexibility. Trade-offs include balancing current enjoyment against future financial security and potential healthcare costs. Choosing when to retire depends on personal priorities, risk tolerance, and expected expenses.
- "Net worth at age 95" projections estimate the total value of all assets minus liabilities at that future age. They are calculated by modeling income, expenses, investment growth, property appreciation, and debt repayment over time. Assumptions include rates of return, inflation, and spending patterns. These projections help assess long-term financial sustainability under different retirement scenarios.
- Downsizing reduces living expenses by lowering housing costs, property taxes, and maintenance fees. Lifestyle changes, like traveling minimally or choosing affordable locations, further cut monthly spending. These adjustments free up more money ...
Counterarguments
- The couple’s net worth is relatively modest compared to their high income, suggesting that their savings rate or investment returns may not be as optimized as possible for their earning level.
- Carrying $1.89 million in property debt introduces significant risk, especially if rental income declines or property values drop.
- Their financial projections assume continued high income and stable investment returns, which may not account for economic downturns or unexpected expenses.
- Relying on employer-provided healthcare until Medicare eligibility could be risky if Jason loses his job or if employer benefits change.
- Their discretionary spending has consistently exceeded their self-imposed "guilt-free" budget, indicating potential challenges in maintaining spending discipline during retirement.
- The scenarios assume willingness and ability to downsize or relocate, which may be more emotionally or logistically difficult than anticipated.
- The analysis does not ...
Get access to the context and additional materials
Money Psychology and Emotional Blocks
Many couples struggle to feel safe about money, regardless of net worth. Laura and Jason serve as a clear example: while they enjoy substantial financial success in their 30s, their lived experience reveals that emotional blocks and early lessons about money can deeply shape how secure—or anxious—people feel, regardless of the facts on paper.
Laura's Anxiety About Financial Security Stems From Childhood Experiences of Loss and Instability
Laura’s anxieties about spending and financial security trace back to her family’s experience during the 2008 financial crisis. Growing up in suburban Southern California, Laura hadn’t thought much about money until her parents lost their house. The family was forced into their first serious conversation about finances, with her father expressing regret and devastation over his inability to pay for Laura’s college. This moment had a lasting impact, as Laura recounts her father still named his inability to provide as one of his biggest regrets when he was dying.
These early experiences planted beliefs that financial failure and the inability to provide are personal shortcomings. As a result, Laura developed what she describes as trauma-level anxiety about spending, which persists even as her and Jason's finances have greatly improved. For example, large purchases trigger strong bodily reactions—she cried over her first home offer and even threw up after buying her first car. This anxiety is not proportional to risk: Laura conflates buying a $78 jean jacket with jeopardizing retirement, feeling that any spending could be financially irresponsible and endanger her future security.
Small and large purchases alike make her feel on edge, and she admits to feeling “good” when she spends less and “bad” when she spends more. Even with significant increases in income and net worth, the anxiety has remained. Laura articulates the lingering fear of “the rug being pulled out from underneath us” and admits that even saying she could simply buy what she wants feels untrue and difficult.
Couple's Pattern Of Never Feeling "Safe" Despite Accumulating Wealth Demonstrates a Disconnect Between Financial Security and Belief-Driven Perceptions of Risk and Loss
Ramit Sethi points out a persistent cycle: despite $1.8 million in net worth, Laura and Jason never truly feel safe about their finances. Laura acknowledges holding onto her savings, enjoying the visible fruits of hard work while simultaneously worrying—her net worth brings satisfaction, but not relief from anxiety. She leaves student loans unpaid for years just to “see” the money in her accounts, and even after debt payments, her feelings about safety don’t shift.
Laura describes restlessness and insecurity at night, endlessly problem-solving and worrying about whether early retirement is even possible, if major spending decisions can be justified, or if they are risking too much by not saving more aggressively. Her anxieties extend into doubts about every financial decision, regardless of mathematical analysis.
Jason and Laura also shift their worries from one perceived vulnerability to another: first about savings, then about market fluctuations, and then to potential healthcare costs in old age. This mindset creates a perpetual cycle of anxiety, unsolvable by accumulation alone. Ramit observes that high-net-worth individuals often justify insecurity by focusing on unpredictable risks like tax policy, market volatility, or catastrophic healthcare needs, rationalizing discomfort instead of addressing the underlying psychological issues with money.
Jason's Optimistic Money View vs. Laura's Pessimistic View
Within the couple, Jason tends to be the financial optimist, constructing models and showing the math for retirement or major purchases. Laura acts as the skeptical counterweight, with Jaso ...
Here’s what you’ll find in our full summary
Money Psychology and Emotional Blocks
Additional Materials
Counterarguments
- While emotional blocks and early experiences can influence financial anxiety, many people successfully overcome such anxieties through education, therapy, or exposure to positive financial experiences, suggesting these patterns are not universally persistent or unchangeable.
- The focus on psychological factors may underplay the role of practical financial literacy and planning, which can empower individuals to feel more secure regardless of past experiences.
- Not all high-net-worth individuals experience persistent financial anxiety; some find that increased wealth does, in fact, alleviate their concerns about security.
- The narrative centers on Laura’s experience, but some individuals with similar backgrounds may develop resilience or a more balanced approach to money rather than ongoing anxiety.
- The suggestion that external validation is necessary for emotional relief may not apply to everyone; many couples find reassurance and confidence through ...
Actionables
- You can create a shared “emotional spending map” with your partner by each drawing or listing situations that trigger financial anxiety or comfort, then compare and discuss where your feelings overlap or differ to spot patterns and start building mutual understanding. For example, you might realize you both feel tense about unexpected car repairs but only one of you feels anxious about dining out, which helps you target conversations and agreements around those specific triggers.
- A practical way to reframe your financial story together is to write a short, positive narrative about your money journey as if you’re looking back from a secure future, then read it aloud to each other monthly to reinforce a new, shared perspective. For instance, you might write, “We learned to trust our decisions and enjoy our resources, knowing we could handle surprises together,” and use this as a touchstone when anxiety arises.
- ...
Get access to the context and additional materials
Couple Communication and Relationship Dynamics Around Money
Financial decisions highlight deep dynamics in Laura and Jason’s relationship, shaped by different earnings, spending habits, and philosophies about money.
Laura and Jason Split Shared Expenses 50-50 Despite Income Difference
Laura and Jason handle finances separately, each controlling their own savings and checking accounts. Anything bought for individual use is paid from personal funds. For joint expenses, they typically split costs 50-50. Larger joint purchases, such as those around $10,000 or more, prompt more detailed discussions.
50-50 Split Burdens Laura, Despite Jason's Higher Earnings and Willingness to Cover Major Expenses
Despite Jason earning significantly more, the couple maintains an even split on most expenses. Laura reflects on the impact, stating that while Jason contributes more for major outlays—like the house’s down payment or when paying off larger purchases—the recurring 50-50 approach can feel unfair given her lower income. She notes moments of questioning the fairness of this system, but acknowledges that Jason routinely covers extra costs in substantial situations, which sometimes leads her to hope things might "even out" over time.
The Couple Hasn't Established a Unified Financial System
Laura and Jason lack a structured or unified approach to combine their finances. Their budgeting for major expenses tends to be informal; for example, with the van build-out, Laura admits she set a budget number based “on nothing other than vibes.” This triggers negotiation rather than systematic planning, with Jason often suggesting a higher amount and then haggling toward agreement. Laura wishes she felt more confident in budgeting and understanding what is realistically affordable, noting Jason’s more analytical approach and encouragement for her to dream bigger about her financial future.
Couple's Spending Philosophies Clash: Laura Justifies Expenses, Jason Enjoys Spending Within Means
Laura’s and Jason’s attitudes towards spending diverge sharply. Laura is cautious, often equating frivolous purchases with moral failings, and she prefers to meticulously justify expenses before buying. In contrast, Jason enjoys spending as long as it stays within their means and often acts on impulse or the appeal of experiences.
Laura Views Frivolous Spending As a Moral Failing, While Jason Is Impulsive and Spends On Experiences and Desired Items
Laura demonstrates her restraint and self-protection in spending by hesitating to buy items she wants, like a $78 jean jacket. She delayed the purchase despite loving the jacket, citing the expense of the year and an internalized sense that such spending was risky. Jason was unaware her reluctance was financial, thinking she simply hadn’t liked the jacket; otherwise, he would have supported the purchase.
Laura's Reluctance to Buy a $78 Jacket Highlights Her Financial Self-Protection Preferences
The story of the jacket underscores Laura’s approach: she is deeply cautious with discretionary spending, sometimes delaying for months and missing out as items sell out. These missed opportunities frustrate her, but they illustrate her underlying philosophy that careful justification is required for every purchase.
Couple Lacks Guidelines, Thresholds, or Shared Values for Aligned Decisions on Shared Rich Life
The lack of agreed thresholds, guidelines, or shared valu ...
Here’s what you’ll find in our full summary
Couple Communication and Relationship Dynamics Around Money
Additional Materials
Counterarguments
- Splitting expenses 50-50, even with an income gap, can be seen as a way to maintain financial independence and avoid resentment about unequal contributions or control.
- Maintaining separate finances may help each partner retain autonomy and reduce potential conflicts over spending priorities.
- Jason’s willingness to cover major expenses could be viewed as a fair way to balance the financial burden, even if day-to-day costs are split evenly.
- An informal, negotiation-based approach to budgeting may foster open communication and flexibility, allowing both partners to adapt to changing circumstances.
- Laura’s cautious approach to spending, while sometimes leading to missed opportunities, may help the couple avoid unnecessary debt or financial risk.
- The lack of a unified financial system does not necessarily indicate dysfunction; some couples thrive with less structure and more individualized approaches.
- Jason’s encouragement for Laura to “thi ...
Actionables
- you can set up a monthly “money moods” check-in where each partner shares how recent spending and saving decisions made them feel, using a simple scale (like green for comfortable, yellow for uneasy, red for stressed), to surface hidden frustrations and open up honest conversations about fairness and comfort levels.
- a practical way to create shared financial boundaries is to draft a “spending comfort map” together, where you each list expense categories and assign a personal comfort threshold (dollar amount or frequency) for each, then compare and negotiate a joint version that respects both perspectives.
- you can build confidence and shared lang ...
Get access to the context and additional materials
Financial Knowledge Gaps and Building Money Competence
Laura Acknowledges Gaps in Understanding Finances, Knowing Balances and Investment Totals but Lacking Comprehension of Cash Flow, Withdrawals, and Money Mechanics
Laura openly admits that while she knows their investment balances and net worth, she doesn’t grasp the deeper mechanics of their finances, tax implications, or how to execute retirement withdrawals with confidence. She describes her knowledge as “very minimal,” mostly limited to account totals and spreadsheet lines, while Jason manages the finer details of their household finances. This lack of understanding leads Laura to uncertainty around major financial moves and withdraws, often leaving her anxious about whether she’s making the right decision.
Laura’s lack of financial confidence is further highlighted when she’s stunned to learn their real household income. She had assumed their combined income was $400,000 or $450,000, but after reviewing their finances, Ramit points out it’s closer to $500,000—a significant difference. Jason’s robust management of their finances means Laura often defers to him, accepting his oversight without understanding the architecture of their system. This dynamic undermines Laura’s financial confidence and leaves her uneasy about making or even questioning financial decisions.
To gain more clarity, the couple completed a Conscious Spending Plan (CSP) using Monarch software. While Laura describes the process as the “least amount of fun” she’s had in a while and admits it was overwhelming to track down all their money, the end result was transformative. Laura notes having “complete transparency with all accounts” and a “better grasp on what’s going on,” shifting their financial conversations from abstract “what if” dreams to more concrete, informed planning.
Enhancing Laura's Financial Literacy Is Key To Shifting From Anxious Decisions To Confident Retirement Planning
Understanding Money Mechanics Is Key To Overcoming Financial Overwhelm
Ramit points out that most people go through life with personal finance remaining abstract and aspirational, rather than actionable and confident. Laura agrees that knowing their net worth and fixed costs doesn’t translate to understanding how money really moves—cash flow, taxes, and the mechanics behind investment withdrawals. She recognizes that becoming more knowledgeable will combat the feeling of being overwhelmed and help her make better, more confident decisions.
Seeing Jason's Models Makes Financial Planning More Concrete For Laura
When Laura suggests actually sitting down with Jason to examine his financial models, she believes it will help make financial planning less abstract and more tangible. Ramit encourages this, noting that when a spouse takes a genuine interest in financial flows and tools, it fosters greater competence, confidence, and control. He suggests Laura and Jason use visual diagrams and shared discussions to clarify their money flows, retirement strategies, and decision-making rationales.
Ramit Urged Laura to Boost Her Financial Knowledge By Reading "I Will Teach You to Be Rich" and Having Discussions With Jason, Suggesting Shared Learning for a Common Financial Language and Framework
Ramit recommends that Laura boost her financial knowledge by reading “I Will Teach You to Be Rich” and engaging in shared learning with Jason, effectively establishing a shared financial language and framework. This collaborative approach is designed to empower Laura, give her clarity, and prepare her for confident retirement planning, shifting the couple’s money talks from intimidating to empowering.
Creating a "Worry-Free Spending Number" Helps Laura Transition From Anxiety-Driven Penny-Pinching to Confident Guideline-Based Spending
...
Here’s what you’ll find in our full summary
Financial Knowledge Gaps and Building Money Competence
Additional Materials
Counterarguments
- Focusing on increasing Laura’s financial knowledge may not address deeper issues of trust or communication within the relationship; knowledge alone does not guarantee confidence or equal participation.
- Some individuals may prefer a division of labor in household finances, finding it efficient and satisfactory rather than problematic, and may not desire full transparency or shared management.
- The emphasis on “worry-free spending numbers” could encourage overspending or reduce healthy financial caution, especially if not regularly reviewed or adjusted for changing circumstances.
- Not everyone benefits from or enjoys structured financial exercises or reading prescriptive finance books; alternative learning styles or approaches may be more effective for some.
- The narrative assumes that anxiety around spending is inherently negative, but for some, cautious spending habits are a rational response to uncertainty or past ex ...
Actionables
- You can create a simple monthly money map by drawing arrows between your income sources, spending categories, and savings accounts to visually track how money moves in and out, helping you see cash flow and spot areas for improvement.
- A practical way to build confidence in financial decisions is to set up a recurring “mini withdrawal” day where you simulate taking out a small, fixed amount from your savings or investment account, then document the steps, tax considerations, and feelings each time to demystify the process.
- You can establish a shared financial check-in ritu ...
Get access to the context and additional materials
Practical Retirement Transition Logistics
Retirement planning often focuses on achieving a financial target, but, as this couple’s experience reveals, the mechanics of shifting from earning a regular paycheck to drawing down investments and pensions can be unexpectedly fraught. Beneath the financial planning lies a thicket of practical and emotional hurdles, from handling day-to-day expenses to managing family support obligations.
Uncertainty Fuels Laura's Anxiety Despite Financial Plan's Viability
Despite ample savings and a viable retirement plan, Laura is anxious about the transition to retirement. She voices her confusion over practical details, such as how they will pay for groceries or travel once their paychecks stop. Although the financial math works, the shift from years of saving and accumulating assets to spending those assets—“de-accumulation”—feels unclear and intimidating. Jason, meanwhile, has started practicing for this shift by saving his paychecks and living only on his $4,300 monthly military pension, giving himself a preview of income in retirement. Laura tries a similar approach, transferring most of her paycheck to savings and maintaining a monthly checking account budget, but both admit the actual logistics still feel murky.
One significant operational question, the arrangement of a joint account for shared retirement expenses, remains unresolved. Their discussions with Ramit Sethi highlight how issues such as how to withdraw funds, handle monthly spending, and cover expenses like travel and groceries are still not fully planned out, which exacerbates Laura's anxiety about the retirement leap.
Ramit Advised the Couple to Simulate Retirement Income Early to Test Systems and Resolve Operational Questions
To address these uncertainties, Ramit Sethi recommends a tangible approach: simulate retirement before it arrives. By establishing a joint account, automatically depositing Jason’s pension, and simulating regular withdrawals (as they would from investments in retirement), the couple can rehearse paying bills and managing spending entirely from retirement income. This exercise allows them to see how money will flow without the safety net of paychecks, revealing practical issues and allowing time to iron out problems before their actual retirement date.
As a result of this simulation, the couple can boost their confidence about the transition, making the process feel more manageable and less overwhelming. Living the retirement system provides real-time feedback—if something isn’t working, they discover it with years to spare, not days. This practical rehearsal helps answer lingering questions about both the mechanics and the mindset required to step confidently into retirement.
Complex Financial Situation With Rental Income, Mortgages, Student Loans, and Investments Requires Professional Guidance
Jason handles most of their finances, diligently researching topics like Roth conversions and withdrawal strategies. Despite the time he’s invested, the complexity—managing rental properties, multiple mortgages, student loans, and investments—can feel overwhelming. He resists paying advisors, preferring to stay hands-on, but acknowledges the process is daunting. Ramit Sethi urges the couple to hire a flat-fee financial advisor. This would give them access to ...
Here’s what you’ll find in our full summary
Practical Retirement Transition Logistics
Additional Materials
Clarifications
- De-accumulation is the phase in retirement when you start spending your saved assets instead of adding to them. It involves creating a sustainable withdrawal strategy to ensure your savings last throughout retirement. This phase requires careful planning to balance income needs with investment risks and longevity. Managing de-accumulation well helps prevent running out of money too soon.
- A Roth conversion involves moving money from a traditional retirement account to a Roth IRA, paying taxes on the converted amount now. This strategy can reduce future required minimum distributions and tax burdens in retirement. It allows tax-free growth and withdrawals later, providing more flexible income planning. Timing and tax rates are key factors in deciding when to convert.
- A flat-fee financial advisor charges a fixed amount for their services, regardless of your investment size or transactions. This contrasts with commission-based advisors, who earn money from selling financial products, potentially creating conflicts of interest. Flat fees provide transparent costs and can encourage unbiased advice focused on your goals. This model suits clients wanting clear pricing and control without ongoing percentage-based fees.
- Simulating retirement income means living for a period using only the money you expect to have in retirement, without relying on your current paycheck. This practice reveals practical challenges like timing bill payments, managing cash flow, and adjusting spending habits. It helps identify and fix issues early, reducing stress and surprises when actual retirement begins. Additionally, it builds confidence by making the transition feel more familiar and manageable.
- A joint account for retirement expenses centralizes money management, simplifying bill payments and tracking shared costs. It helps couples coordinate spending without confusion over who pays what. Automating income deposits and withdrawals from this account mimics retirement cash flow, revealing practical issues early. This setup fosters transparency and reduces financial stress during the transition.
- Managing rental income, multiple mortgages, and student loans simultaneously requires tracking diverse cash flows and payment schedules. Rental income must be reported for taxes and balanced against mortgage payments and maintenance costs. Mortgages involve principal, interest, and escrow payments that vary by property and loan terms. Student loans add fixed or variable monthly obligations, complicating overall budgeting and cash flow management.
- Supporting an aging parent can increase monthly expenses and reduce the funds available for retirement savings or spending. It may require additional housing costs, healthcare expenses, or financial gifts, impacting the retiree’s budget and cash flow. This responsibility can also affect the timing of retirement, as individuals might delay retiring to maintain income. Planning for these costs early helps avoid financial strain and ensures stable support for both the parent and the retiree.
- Elderly parents can live independently, rent ...
Counterarguments
- While simulating retirement income can be helpful, it may not fully capture the unpredictability of actual retirement expenses, such as unexpected healthcare costs or market downturns.
- Not all retirees need to hire a financial advisor; some may have sufficient financial literacy and simpler situations that make self-management both feasible and cost-effective.
- The anxiety around "de-accumulation" is not universal; some individuals find spending accumulated assets liberating rather than intimidating.
- Establishing a joint account for retirement expenses is not the only effective method; some couples successfully manage finances with separate accounts and clear communication.
- The focus on cash flow simulation and operational logistics may overlook the importance of psychological and social adjustments to retirement, such as find ...
Get access to the context and additional materials


Create Summaries for anything on the web
Download the Shortform Chrome extension for your browser