
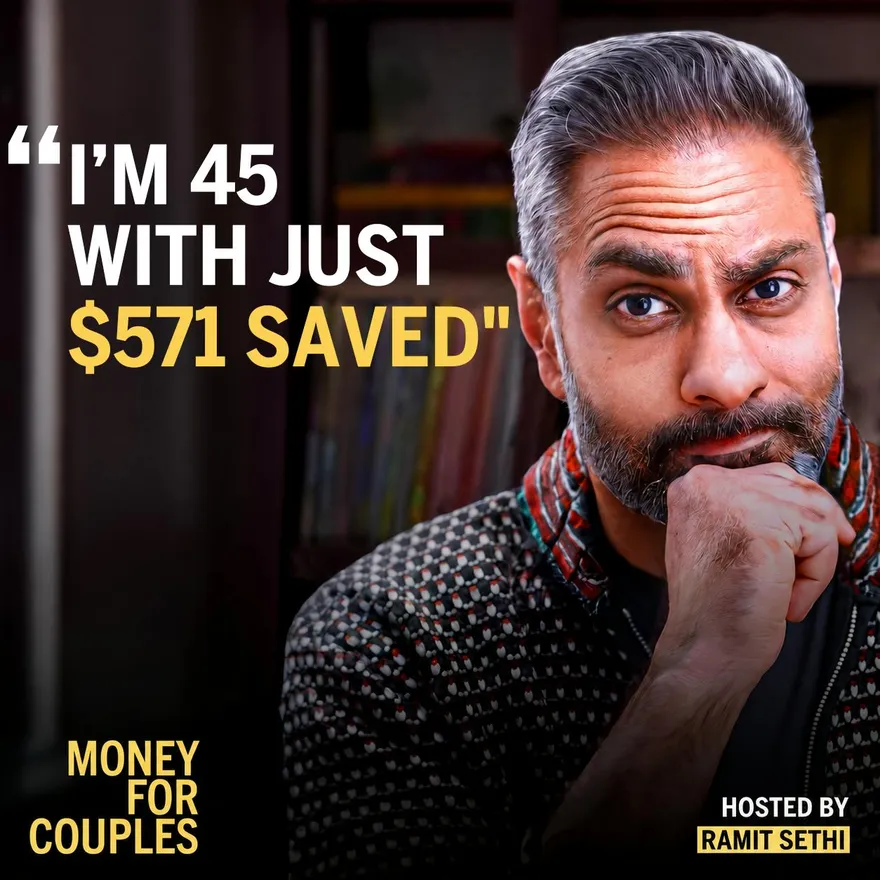
283. “We have 3 kids and live paycheck to paycheck. Are we screwed?”
In this episode of I Will Teach You To Be Rich, Ramit Sethi works with Michelle and Jeff, a couple earning $178,000 annually yet living paycheck to paycheck with $186,000 in debt and a negative net worth. Despite their substantial income, their fixed costs consume 87% of their take-home pay, leaving them vulnerable to declined cards and constant financial stress. The episode examines their pattern of emotional, impulsive spending—including a $76,000 car purchase and $9,235 spent dining out in eight months—and how childhood poverty, financial trauma, and untreated ADHD fuel their money behaviors.
The conversation also addresses the unhealthy financial dynamic between Michelle and Jeff, where Michelle controls all finances while Jeff avoids responsibility and must ask permission for purchases over $20. Together, they develop a shared money philosophy centered on becoming debt-free, establish concrete spending rules, and commit to weekly financial discussions. Jeff agrees to seek medical evaluation for ADHD, and both partners pledge to break cycles of financial secrecy inherited from their parents.

This is a preview of the Shortform summary of the Oct 20, 2026 episode of the I Will Teach You To Be Rich
Sign up for Shortform to access the whole episode summary along with additional materials like counterarguments and context.
1-Page Summary
Couple's Dire Finances: Living Paycheck-To-Paycheck on $178k Income
Michelle and Jeff earn a combined gross income of $178,000, taking home $10,600 per month, yet experience constant financial stress. Despite their substantial income, they struggle to cover essentials, sometimes facing declined cards and worrying about basic needs like getting their children to school or doctor appointments. Michelle describes their situation as "just piecing things together" to survive from paycheck to paycheck.
Ramit Sethi highlights that their fixed monthly costs consume 87% of their take-home pay, leaving minimal margin for emergencies and creating constant instability. While their rent is relatively low at $1,695, high car payments of $1,000 monthly for a $76,000 Nissan Pathfinder, along with utilities and other recurring costs, leave them with almost nothing each month. Their assets total just $26,800, with investments of only $264 and cash savings of $571—meaning any unexpected expense triggers more debt.
The couple carries $186,000 in total debt, including $65,000 in student loans, a $48,000 car loan, and multiple high-interest debts (credit cards at 18.4% and personal loans at 17.5%), resulting in a negative net worth of $159,170. Retirement savings are essentially nonexistent, with only $117,000 projected by retirement. Michelle admits to contributing just 1% to their 401(k) due to fears of losing take-home income.
Their spending reveals chronic overspending driven by emotional impulses rather than intentional planning. In eight months, they spent $9,235 on dining out. During a spring break Vegas trip, they spent $2,747 on meals alone. Major purchases are frequently impulsive—the $76,000 Pathfinder was bought after receiving a promotional flyer, with Jeff describing it as feeling like a reward. Looking back, both recognize it increased their monthly payments by $300 and was a poor decision. Jeff estimates that 90% of his spending is emotional and self-justified.
Other large expenses include a $3,000 furniture loan taken while Michelle was grieving her mother's passing, and multiple buy-now-pay-later purchases. The couple admits that this pattern of "it felt like we needed it" drives reckless spending. When emergencies happen, there's little deliberation—the solution is often more debt. They've even considered bankruptcy. Recently, they enrolled in a nonprofit debt management plan to lower interest rates and have removed pay-later apps to break the cycle.
Unhealthy Relationship: Michelle's Control and Jeff's Avoidance
Michelle and Jeff's financial dynamic has created deep stress and resentment, fueled by unequal responsibility and persistent conflict over spending.
Since the start of their relationship, Michelle has managed all household finances—handling taxes, insurance, and budgeting while Jeff deliberately remains ignorant about money. He gives Michelle his paycheck, rarely checks pay stubs, and must ask her how much he earns annually. Jeff admits that for him, ignorance is "bliss," though he acknowledges it's selfish and unfair to let Michelle carry the entire burden.
Jeff is self-described as an impulse buyer, leading them to establish a rule: he cannot spend more than $20 without Michelle's permission. Despite this, he frequently makes expensive requests—a $2,000 smoker, a new TV—even when he knows the answer will likely be "no." He continues to push, hoping Michelle will cave, admitting there's a "50-50" chance she will. Because she manages the money and must often deny Jeff's requests, Michelle feels more like an authoritarian parent than a partner. She's forced to defend her decisions and enforce discipline, leaving her feeling overwhelmed, frustrated, and anxious.
This parent-child pattern began in 2010 after their first child, when Michelle made the conscious decision to take full control and start consistently saying "no" to protect their finances. This dynamic has endured for over 15 years, with Michelle absorbing all of Jeff's inquiries while taking on the emotional and practical burden herself. When Michelle does give in to Jeff's requests, the family's debt increases, which only reinforces Jeff's belief that persistence works. Both recognize that Michelle ultimately bears the brunt of managing and correcting the fallout, while Jeff is insulated from consequences by his willful avoidance.
Psychological Roots: Childhood Trauma, ADHD, and Money Behavior
The couple's financial behaviors are deeply rooted in their childhood experiences, emotional histories, and neurodivergence.
Jeff grew up in poverty, often lacking basic needs like electricity and running water. He describes eating government-issued cheese, sometimes being unable to afford school meals, and having to pay his parents rent as early as age fourteen. There was little communication about money—his family didn't discuss financial difficulties and operated in survival mode. This shaped an ingrained association between money and stress, silence, and survival. After leaving home at 24, Jeff lived in an RV and began spending impulsively without considering long-term consequences. He holds a fatalistic worldview, often questioning the value of planning for the future, citing examples like violence and random accidents. Jeff's relationship with his father, a drill sergeant often disappointed in him, has led to an ongoing need to prove himself through purchases.
Michelle's family was lower-middle-class and barely getting by, with memories of evictions and silent financial stress. Her parents responded to financial problems by saying "no" without explanation—a communication strategy Michelle now uses with her own family. Both Michelle and Jeff experienced parental misuse of their financial resources, including maxed-out credit cards and forged signatures. Financial betrayals left Michelle anxious, fixating on saving $2,500 for her future cremation as her primary financial goal. Ramit challenges her to dream beyond survival goals and instead focus on building a rich, fulfilling life.
Jeff recognizes ADHD patterns in himself—difficulty focusing, impulsivity, and poor planning—especially after his son was diagnosed. However, Jeff refuses to seek evaluation or treatment, citing a general dislike of doctors and fear of having his behavior deemed mere personality rather than a treatable condition. Jeff tends to disengage during financial discussions, acknowledging that ADHD symptoms make it hard for him to focus when Michelle tries to show him numbers or budgets. His avoidance of diagnosis and general neglect of his health increases Michelle's stress and impedes their financial and relational progress.
Ramit also identifies Jeff's "oppositional reflex"—reflexive opposition and disagreement even when suggestions are positive—linking it to Jeff's upbringing under a critical, directive father. This impulse to contradict creates obstacles to partnership, and Ramit urges Jeff to address it in therapy for the sake of his relationship and well-being.
Creating Change: Shared Money Philosophy, Rules, & Weekly Communication
Michelle and Jeff have implemented a structured approach to transforming their finances, built on a shared philosophy, clear rules, and ongoing communication.
The couple's foundational money philosophy is to become "a debt-free family." Both explicitly commit to making changes in their spending and financial behaviors to support this goal. Michelle proposes and they agree to save 7% of their net pay monthly. They schedule a non-negotiable weekly money conversation every Sunday at 11 a.m., committing to review spending, set goals, and make collaborative decisions. By establishing this philosophy, Michelle and Jeff create a north star to guide their daily decisions against temptation.
To support their philosophy, they formalize practical rules that serve as guardrails. They commit to evaluating discretionary spending against their financial plan before purchases. A specific rule is set: Jeff commits never to manipulate Michelle regarding financial discussions. They restrict eating out to a single monthly treat, capped at $75. Rules are written down, referenced regularly, and used to hold each other accountable.
The couple acts swiftly to align their budget with their philosophy. By switching cell phone plans, their monthly bill drops from $446 to $85, lowering fixed costs from 87% to 76% of take-home pay. They reduce grocery spending from $2,000 to $1,500 monthly by budgeting rather than sale shopping. They increase emergency fund savings from $150 to $750 per month and allocate an additional $500 monthly for aggressive debt repayment. They also restructure their banking to include dedicated accounts for bills, groceries, and discretionary spending.
Michelle acknowledges that managing finances alone caused her significant anxiety and blocked Jeff's involvement. She commits to bringing Jeff fully into financial discussions, recognizing she can't carry the burden alone. Jeff pledges to ask more questions, learn about their household finances, and share ownership, shifting the dynamic to true partnership. As both partners seek higher-earning jobs, they agree that any additional income will be allocated automatically toward savings and debt repayment, avoiding lifestyle inflation.
Accountability: Jeff's Evaluation Commitment and Both Partners' Cycle-Breaking Commitment
Jeff agrees to seek a medical evaluation to address longstanding behavioral patterns that impact both his mental health and the family's financial well-being. He commits to talking with a doctor about possible ADHD and related concerns, reaffirming his readiness to listen to professional recommendations after years of resistance. Jeff acknowledges his tendency toward reflexive disagreements—a pattern learned from his drill sergeant father—and recognizes the need for professional support to change this ingrained behavior. For years, Jeff avoided doctors despite Michelle's encouragement, but recently he has made significant steps outside his comfort zone, including returning to school and applying for new positions. Personal accountability is crucial, as Michelle has endured the consequences of Jeff's untreated ADHD and impulsive spending for two decades.
Both Jeff and Michelle recognize patterns of secrecy and poor financial communication inherited from their parents and commit to breaking these cycles. Michelle strongly opposes her parents' practice of hiding financial struggles and simply telling her "no" without explanation. Instead, she pledges transparency with their children, openly discussing costs and budgeting decisions. When their son asks about expenses or savings, Michelle now answers candidly, sharing information and preparing him for future financial independence. Jeff also commits to a more open approach, supporting discussions about debt management, savings, and planning for the future.
Michelle and Jeff are determined to create a new financial legacy for their children, different from the one they inherited. They vow to protect their children from past harms like fraud and identity theft—both experienced forged signatures and unauthorized credit opened in their names by their own parents. By breaking these patterns, they aim to demonstrate that seeking help, asking questions, and responsible money management are not only possible but necessary for safeguarding the next generation's future.
1-Page Summary
Additional Materials
Counterarguments
- While Michelle and Jeff's financial stress is significant, their income is well above the national median, suggesting that their situation is primarily the result of personal financial choices rather than systemic economic hardship.
- The decision to purchase a $76,000 vehicle with a $1,000 monthly payment, despite already being in debt, reflects a lack of financial discipline rather than necessity.
- Their high fixed costs are largely self-imposed and could be reduced further by making different lifestyle choices, such as driving a less expensive car or cutting discretionary spending more aggressively.
- The pattern of emotional and impulsive spending is acknowledged by both partners, indicating that their financial instability is not due to lack of knowledge but rather lack of self-control and accountability.
- Michelle's unilateral control over finances, while intended to protect the family, may perpetuate Jeff's financial disengagement and prevent the development of true partnership and shared responsibility.
- Jeff's refusal to seek evaluation or treatment for suspected ADHD, despite recognizing its impact, is a personal choice that prolongs the family's financial and relational difficulties.
- The couple's focus on breaking generational cycles is commendable, but their current actions (such as continued overspending and accruing debt) may undermine their stated goals unless consistently addressed.
- Their projected retirement savings are low, but their relatively high income provides an opportunity to make significant progress if they prioritize long-term planning over short-term gratification.
- The narrative emphasizes emotional and psychological roots for their financial behavior, but practical financial education and stricter adherence to budgeting could yield immediate improvements regardless of past trauma.
- While transparency with children about finances is positive, exposing them to ongoing financial stress and conflict may have unintended negative effects.
Actionables
- you can set up a weekly five-minute “money mood check-in” with your partner or family where each person shares how they felt about money decisions that week, helping to spot emotional triggers before they lead to impulsive spending; for example, if someone felt anxious before a big purchase, talk about what caused it and brainstorm a healthier response for next time.
- a practical way to reduce emotional spending is to create a “cool-off cart” in your phone’s notes app where you list any non-essential item you want to buy, then wait 72 hours before deciding; after the waiting period, review the list together and discuss whether the desire to buy is still strong or if it was just a passing urge.
- you can build trust and transparency by scheduling a monthly “financial story night” where you and your partner or family members each share a personal money memory—good or bad—and discuss how it shapes your current habits, making it easier to understand each other’s behaviors and break negative cycles.
Get access to the context and additional materials
Couple's Dire Finances: Living Paycheck-To-paycheck on $178k Income
Michelle and Jeff Face Financial Stress From Debt and High Fixed Costs Despite Substantial Income
Michelle and Jeff earn a combined gross income of $178,000, taking home $10,600 per month, yet still experience tremendous financial stress. Despite what seems like a comfortable income, they struggle to cover essentials, sometimes facing declined cards and worrying about how to pay for their children’s needs, such as getting kids to school or children’s doctor appointments. Michelle describes their situation as “just piecing things together” to get from one paycheck to the next, likening their struggles now to those they faced two decades ago, despite a bigger paycheck.
Ramir Sethi highlights that their fixed monthly costs consume 87% of their take-home pay, leaving them with little margin for emergencies. This creates constant financial instability. Their rent, at $1,695, is relatively low at 11.39% of take-home pay, thanks to a generous landlord, but high car payments ($1,000/month for a $76,000 Nissan Pathfinder), utilities, and other recurring costs leave them with almost nothing left each month. Assets stand at $26,800, investments a mere $264, and cash savings only $571. This tiny emergency fund means that any unexpected expense will likely trigger more debt.
The couple’s total debt totals $186,000—including $65,000 in student loans, a $48,000 car loan, and multiple high-interest debts (credit cards at 18.4% and personal loans at 17.5%), resulting in a negative net worth of $159,170. Retirement savings are essentially nonexistent, with only $117,000 projected by the time Michelle reaches retirement if their current trajectory continues. Michelle admits to minimal contributions, just 1% into their 401(k), due to fears of losing take-home income.
Their $571 in savings means even small emergencies or repairs would require new borrowing. This has led to desperate measures, like juggling payments, skipping some bills, or making partial payments just to get by each month. Both Michelle and Jeff acknowledge that they “spend more than we make,” and the fear and stress of living this close to disaster permeates every aspect of their lives.
Couple's Spending Shows Chronic Overspending Driven by Emotional Impulses, Not Intentional Financial Planning
The couple’s spending reveals a pattern of chronic overspending, often tied to emotions rather than a deliberate financial plan. In just eight months, they spent $9,235 on dining out. During one spring break trip to Las Vegas with their daughters, they spent $2,747 on meals alone, rationalizing the splurge as a special occasion to be dealt with later.
Major purchases are frequently impulsive and emotionally charged. The $76,000 Nissan Pathfinder was bought after the couple received a promotional flyer suggesting an upgrade—Jeff describes the purchase as feeling like a reward for past effort and a way to guarantee reliability in harsh winters. Looking back, both recognize it was a poor decision that increased their monthly payments by $300. This emotional spending is a recurring theme; Jeff estimates that 90% of his spending is emotional and self-justified.
Other large expenses include a $3,000 furniture loan, taken out while Michelle was grieving her mother’s passing and wanted to make their inherited living space feel new. Even everyday items, like televisions, were purchased using Klarna’s buy-now-pay-later app when two TVs broke within a week.
The couple admits that this pattern of “it felt like we needed it” is driving reckless spending. They have eight pets and three children, increasing daily obligations and costs. When emergencies happen—like broken electron ...
Here’s what you’ll find in our full summary
Couple's Dire Finances: Living Paycheck-To-paycheck on $178k Income
Additional Materials
Counterarguments
- While Michelle and Jeff’s financial stress is real, their situation is primarily the result of personal financial decisions—such as purchasing a $76,000 vehicle and spending heavily on dining and vacations—rather than solely external economic pressures.
- Their rent is notably low for their income and region, suggesting that housing costs are not the main driver of their financial instability.
- Many families with similar or lower incomes manage to save and avoid high-interest debt by prioritizing essential expenses and limiting discretionary spending.
- The couple’s pattern of emotional and impulsive spending, as acknowledged by themselves, indicates that improved financial literacy and discipline could significantly improve their situation.
- Their minimal retirement savings and lack of emergency fund are consequences of current spendi ...
Actionables
- you can set up a weekly five-minute “spending pause” where you review your planned purchases for the week and rate each one on a scale of 1–5 for emotional motivation, then challenge yourself to delay or skip anything rated 4 or 5; this helps you spot and interrupt emotional spending before it happens.
- a practical way to prevent chronic overspending is to create a “fixed cost lockbox” by moving the exact amount needed for recurring bills into a separate checking account right after payday, so you can’t accidentally spend it on non-essentials.
- you can run a “future self audit” by w ...
Get access to the context and additional materials
Unhealthy Relationship: Michelle's Control and Jeff's Avoidance
Michelle and Jeff's financial dynamic has led to deep-seated stress and resentment, fueled by an unequal division of responsibility and persistent conflict over spending.
Control of Household Finances Creates Parent-Child Dynamic, Causing Stress and Resentment
Michelle Manages all Finances Alone Since the Relationship Began
Since the start of their relationship, Michelle has managed all the household finances. It began informally, with Michelle taking Jeff’s money in Monopoly, and soon she was handling taxes, insurance, and budgeting because she had more experience living independently. This arrangement continued as their relationship progressed and particularly solidified after the birth of their first child. Michelle has been solely responsible for ensuring bills are paid and the family stays afloat, often feeling she's just "piecing things together" to survive from paycheck to paycheck.
Jeff Avoids Financial Knowledge, Preferring Ignorance to Reduce Anxiety, but Admits It Unfairly Burdens Michelle
Jeff deliberately remains ignorant about their finances. He gives Michelle his paycheck, rarely checks his pay stubs, and must ask her how much he earns annually. He recently had no involvement even in setting up his own 401k. Jeff admits that for him, ignorance is "bliss"—avoiding the stress and anxiety that thinking about money brings. Though he acknowledges it's selfish and unfair to let Michelle carry the entire burden and make her the "bad guy," he finds it easier to focus on other responsibilities around the house.
Jeff Is an Impulse Buyer Who Gives His Paycheck to Michelle, Asks For Permission For Purchases Over $20, but Still Pushes Boundaries With Costly Requests ($2,000+ Smoker, New Tv), Knowing Michelle Will Likely Say No
Jeff is the first to say he is an impulse buyer, leading them to establish a rule: he cannot spend more than $20 without Michelle’s permission. Despite this, he frequently makes expensive requests—for example, asking for a $2,000 smoker or a new TV. Even when he knows the answer will almost surely be "no," he continues to push, hoping to persuade Michelle. He recognizes the pattern, saying there’s a "50-50" chance she’ll cave in, and admits he tends to buy things impulsively and deal with the financial consequences later, which usually fall on Michelle.
Michelle Feels Authoritarian, Not Equal Partner, By Denying Jeff's Requests and Enforcing Financial Discipline, Leaving Her Frustrated, Anxious, and Worried About Making Ends Meet
Because she manages the money and must often deny Jeff’s requests, Michelle feels more like an authoritarian or a parent than a partner. She is forced to defend her decisions, explain reasons for denial, and enforce discipline. This leaves her feeling overwhelmed, frustrated, and anxious. She resents being put in this position, especially since Jeff often seems to enjoy the debate or ignores the pressure it puts on her. Michelle says it feels intentional and is not "cool" that Jeff knowingly repeats this behavior.
Conflict Cycle: Jeff's Spending vs. Michelle's Restrictions Leaving Both Resentful
Jeff Uses Persistent Persuasion, Questioning Michelle to Sway Her Purchase Decision Despite Expecting a No
Jeff describes scenarios, like the request for the smoker, where he persists even after practical objections are raised—offering alternative solutions or rationalizations to wear Michelle down. Ramit likens this to a cycle where Jeff’s persistent questioning forces Michelle into providing repeated denials and justifications, and neither walks away feeling good. Jeff admits to asking even when he knows the answer, because “sometimes she’ll crack.”
Michelle Adopted This Pattern In 2010 to Protect the Family's Finances By Saying "No," Leading To 15 Years of Stress, Control, and Arguments
Michelle made the conscious decision in 2010—af ...
Here’s what you’ll find in our full summary
Unhealthy Relationship: Michelle's Control and Jeff's Avoidance
Additional Materials
Clarifications
- A 401(k) is a retirement savings plan sponsored by an employer that allows employees to save and invest a portion of their paycheck before taxes. Managing a 401(k) involves choosing how much to contribute and selecting investment options, which affects long-term financial security. Jeff’s lack of involvement means he is not actively planning for his future or understanding their overall financial health. This can increase Michelle’s burden and risk their financial stability.
- Impulse buying can quickly deplete household savings and increase debt, creating financial instability. It often leads to conflicts when one partner feels burdened by unplanned expenses. Over time, this behavior can erode trust and cause resentment between partners. Managing impulse purchases requires clear communication and agreed-upon spending limits.
- A "parent-child dynamic" in adult relationships occurs when one partner takes on a controlling or decision-making role, while the other becomes passive or dependent. This dynamic often involves one person enforcing rules and the other complying, similar to how a parent manages a child. It can create imbalance, reducing mutual respect and equality. Over time, this can lead to resentment and stress for both partners.
- Michelle feels like an "authoritarian" because she must enforce strict financial rules and deny requests, similar to a parent disciplining a child. This role creates an imbalance, where she holds decision-making power alone without shared input. The dynamic reduces her sense of partnership and mutual respect in financial matters. It also increases her emotional burden, as she faces resistance and must justify her decisions repeatedly.
- Persistent financial requests and repeated denials create ongoing tension and erode trust between partners. This dynamic often leads to feelings of frustration, helplessness, and emotional exhaustion. Over time, it can shift the relationship balance, fostering resentment and reducing open communication. Such stress undermines intimacy and mutual support, weakening the partnership.
- Shared decision-making in household purchases means both partners discuss and agree on spending choices together. It fosters mutual respect, reduces conflict, and ensures financial goals align. Without it, one partner may feel controlled or excluded, causing resentment. Collaborative decisions help build trust and financial stability in relationships.
- Persistent persuasion wears down the person being asked by creating repeated pressure to change their decision. This pressure leads to frustration and emotional exhaustion, as they must continually defend their position. Over time, the asker feels justified in pushing boundaries, while the denier feels controlled and disrespected. This dynamic fosters ongoing conflict and mutual resentment, damaging trust and communication.
- When one partner consistently absorbs financial burdens and emotional stress, they often experience chronic anxiety and burnout. This imbalance can erode trust and intimacy, leading to emotional distance in the relationship. Over time, the stressed partner may develop resentment, which can cause communication breakdowns and conflict escalation. Persistent stress also increases the risk of mental health issues like depression and lowers overall relationship satisfaction.
- Financial responsibility often influences power dynamics by giving the person who controls money more decision-making authority. This control can create imbalances, making the other partner feel dependent o ...
Counterarguments
- Michelle’s management of finances may have initially been a mutually agreed-upon arrangement based on her experience, rather than an act of control.
- Jeff’s avoidance of financial matters could be a coping mechanism for anxiety, not simply irresponsibility or selfishness.
- The rule requiring Jeff to ask for permission for purchases over $20 may have been established collaboratively to prevent financial instability, not solely as a means of control.
- Michelle’s feelings of being an authoritarian may stem from the structure of their arrangement, not necessarily from Jeff’s actions alone.
- Jeff’s persistent requests could be interpreted as attempts to participate in financial decisions, albeit in an unproductive way.
- Occasional compliance with Jeff’s requests ...
Get access to the context and additional materials
Psychological Roots: Childhood Trauma, ADHD, and Money Behavior
The financial behaviors of Jeff and Michelle are deeply rooted in their childhood experiences, emotional histories, and neurodivergence, shaping how they approach money, planning, and relationships.
Jeff's Scarcity Mindset From Childhood Poverty Leads To Impulsive Spending and Lack Of Planning
Jeff's Childhood Poverty and Money-Survival Stress Association
Jeff grew up in poverty, often lacking basic needs like electricity and running water. He describes eating government-issued cheese, sometimes being unable to afford school meals, and having to begin paying his parents rent as early as age fourteen. The family’s income slightly exceeded the poverty line, leaving them ineligible for full government assistance but still struggling.
There was little communication about money; Jeff’s family didn't discuss financial difficulties and didn’t ask for help. Instead, they operated in survival mode—simply dealing with whatever hardship came along. This shaped an ingrained association between money and stress, silence, and survival.
After Leaving Home At 24, Jeff Moved Into an RV, Focusing On the Present Instead of Future Consequences
After leaving home at 24, Jeff lived in an RV on his parents’ property, continuing to pay them rent. Following his divorce, with some disposable income and minimal responsibilities, Jeff began spending impulsively and admits he doesn't consider long-term financial consequences, focusing on immediate gratification instead.
Jeff's Cynical Worldview: Why Plan For the Future if "We Could all Be Hit by a Truck"?
Jeff holds a fatalistic worldview, often questioning the value of planning for the future in a world filled with unpredictable dangers. He cites examples like violence in public places and random accidents, illustrating his reluctance to plan ahead since he believes disaster can strike at any time.
Jeff's Purchases For Self-Validation of Success and Competing With His Father's Approval Drives Jeff's Purchases
Jeff's relationship with his father, who was a drill sergeant and often disappointed in him, has led to an ongoing need to prove himself. He admits to making purchases, such as a smoker, specifically to compete with or emulate his father. This approval-seeking extends into his broader spending habits, with Jeff stating that he is always striving to be better than his father and to parent differently.
Michelle's Financial Anxiety Stemming From Childhood Instability
Michelle Grew Up In a Struggling Lower-Middle-Class Family Facing Evictions and Silent Financial Stress
Michelle’s family was lower-middle-class and often barely getting by, evidenced by her memories of financial stress and parental arguments. She recalls her mother being unable to open a checking account due to bounced checks and being told not to answer the door to avoid utility shutoff notices. Discussions about money were rare and uncomfortable.
Parents Taught Her to Say "No" To Financial Problems Without Explanation, a Communication Habit She now Uses With Jeff and Her Children
Michelle’s parents responded to financial problems by saying “no” to requests without explanation, a communication strategy Michelle now uses with her own family.
Michelle's Parents Misused Her Financial Accounts, Leaving Her Feeling Betrayed
Both Michelle and Jeff experienced parental misuse of their financial resources. Michelle’s mother maxed out a credit card in her name, and her father used her checking information without her consent. Jeff’s parents forged his signature on checks when bank statements were sent home.
Michelle Worries About Parents' Finances, Obsessed With Saving $2,500 For Cremation
Financial betrayals and instability left Michelle anxious about her parents’ and her own long-term arrangements. She fixates on saving $2,500 for her future cremation, perceiving it as her primary financial goal to prevent her children from facing similar hardship.
Michelle's Goal on the Show Was to Ensure Her Children Could Afford Her Cremation, Which Ramit Saw As a Mindset Shaped by Scarcity, Loss, and Fear Instead of Building a Rich Life
Michelle’s fixation on cremation costs illustrates a mindset ruled by scarcity and fear. Ramit challenges her to dream beyond survival goals and instead focus on building a rich, fulfilling life—a perspective shift away from anxiety-driven financial decision-making.
Jeff Likely Has Undiagnosed ADHD Impacting Impulsivity, Focus, and Planning, yet Avoids Medical Evaluation
Jeff Sees ADHD Patterns In Himself From His Son's Diagnosis but Refuses Evaluation or Treatment
Jeff recognizes ADHD patterns in himself—difficulty focusi ...
Here’s what you’ll find in our full summary
Psychological Roots: Childhood Trauma, ADHD, and Money Behavior
Additional Materials
Counterarguments
- While Jeff's childhood poverty and lack of financial education influenced his current behaviors, many individuals with similar backgrounds develop strong financial planning skills as a response, suggesting that personal agency and later-life experiences can also play significant roles.
- Jeff's fatalistic worldview may be a coping mechanism, but some might argue that planning for the future is a rational response to uncertainty, and many people find security and peace of mind through preparation despite life's unpredictability.
- The focus on Jeff's need for his father's approval as a primary driver of his spending may overlook other possible motivations, such as personal interests or social influences unrelated to family dynamics.
- Michelle's fixation on saving for cremation, while rooted in fear and scarcity, could also be seen as a practical and responsible step to prevent burdening her children, rather than solely a sign of a limiting mindset.
- The narrative emphasizes undiagnosed ADHD as a major factor in Jeff's behavior, but similar patterns of impulsivity and avoidance can arise from other causes, such as stress, anxiety, or learned habits, and not all indi ...
Actionables
- you can create a personal money story timeline to identify how your early experiences and family attitudes toward money shape your current financial behaviors and stress triggers; draw a simple timeline, mark key money-related events from childhood to now, and jot down how each event made you feel and how it influences your decisions today.
- a practical way to break the cycle of silent or uncomfortable money conversations is to set a recurring, low-pressure "money check-in" with a trusted friend or partner where you each share one financial worry and one financial hope, focusing on listening rather than problem-solving.
- you can experime ...
Get access to the context and additional materials
Creating Change: Shared Money Philosophy, Rules, & Weekly Communication
Michelle and Jeff have implemented a structured approach to transforming their family finances, built on a shared philosophy, clear rules, and ongoing communication. Their intentional system addresses past challenges and creates a path toward financial health.
Couple's Unified Money Philosophy Prioritizes Debt Elimination, Savings, and Transparency For Change
Michelle and Jeff's Philosophy: "a Debt-Free Family," Guides Their Spending Decisions and Provides a Clear, Motivating Goal Supported by Both Partners Through Action
The couple’s foundational money philosophy is to become "a debt-free family." Both Michelle and Jeff explicitly commit to making changes in their spending and financial behaviors to support this goal.
Michelle Prioritizes Saving 7% of Net Pay Monthly
Michelle proposes and the couple agrees to prioritize saving 7% of their net pay every month. This specific savings rate provides structure, pushes them towards greater financial security, and anchors their long-term planning.
Agreed Weekly Non-negotiable Sunday 11 A.M. Money Talks
Transparency and open discussion are core to their practice. They schedule a non-negotiable weekly money conversation every Sunday at 11 a.m. Both partners commit to this routine as a way to review their spending, set and adjust goals, and make collaborative decisions—fostering a habit of regular, healthy communication about money.
Money Philosophy Explains "why" Behind Decisions, Guiding Couples to Choose Based On Shared Values Over Impulses or "Shiny" Purchases
By establishing a philosophy—debt freedom, targeted savings, and weekly talks—Michelle and Jeff create a north star to guide their daily decisions. When faced with temptation, such as an unplanned purchase or a big-ticket item, they measure decisions against their philosophy instead of giving in to momentary desires.
Couple Develops Money Rules As Philosophical Guardrails For Decision-Making
To support their philosophy, Michelle and Jeff formalize practical rules that serve as "guardrails" for spending and decision-making.
Rule: "Evaluate Discretionary Spending Against Financial Plan Before Purchase"
They commit to running the numbers before any discretionary purchase, ensuring that decisions align with their broader financial goals rather than impulses.
Commitment: Avoid Manipulating Michelle
A specific rule is set: Jeff commits never to manipulate Michelle regarding financial discussions or decisions, reinforcing honesty and fair partnership.
Limit Eating Out to $75/Month For one Monthly Treat
The couple restricts eating out to a single monthly treat, capped at $75. This limit includes all eating-out expenses, from coffee stops to family meals, embodying intentional indulgence without derailing their plan.
Rules for Practical Decision-Making
Rules are written down, referenced regularly, and can be used to hold each other accountable and defuse disagreements. Examples include running spending decisions past the plan and ensuring conversations are open and honest.
Couple's Budget Changes Reduce Costs, Advance Financial Goals
Michelle and Jeff act swiftly to bring their budget into alignment with their philosophy and rules, creating measurable changes.
Cell Phone Bill Cut From $446 to $85/Month, Reducing Fixed Costs From 87% to 76% of Take-Home Pay
By switching cell phone plans, their monthly bill drops dramatically, lowering the portion of their income spent on fixed costs and freeing up cash flow for savings and debt repayment.
They Reduced Grocery Spending From $2,000 to $1,500 Monthly By Budgeting Over Sale Shopping, Increasing Savings Despite Thinking They Were Smart Shoppers
Initially confident in their sale-shopping strategies, Michelle and Jeff realize they overspend on groceries. By setting a strict budget ($1,500), shopping to a number, and tracking weekly spending, they manage to trim $500 monthly and redirect those savings.
Increased Emergency Fund Savings From $150 to $750 per Month
With greater budget clarity, they increase automatic contributions to their emergency fund from $150 to $750 each month, in direct line with their 7% savings goal and providing greater security.
Additional $500/Month Allocated For Aggressive Debt Repayment
Freed-up money from cost cutting is allocated to more aggressive debt repayment, helping them build momentum and see rapid progress toward their d ...
Here’s what you’ll find in our full summary
Creating Change: Shared Money Philosophy, Rules, & Weekly Communication
Additional Materials
Counterarguments
- Strict adherence to a single savings rate (7%) may not be optimal for all financial situations, as flexibility might be needed for unexpected expenses or changing circumstances.
- Limiting eating out to $75 per month could be overly restrictive for some families, potentially reducing opportunities for social engagement or enjoyment.
- Weekly scheduled money talks, while promoting transparency, may feel burdensome or stressful for some couples, potentially leading to conflict or fatigue.
- Relying heavily on rules and structured accounts may create rigidity, making it harder to adapt to unforeseen financial needs or opportunities.
- Focusing primarily on debt elimination and savings might deprioritize other important financial goals, such as investing for long-term growth or allocating funds for personal development and experiences.
- The approach assumes both partners have equal financial literacy and interest, which m ...
Actionables
- you can create a shared digital vision board with your partner that visually represents your joint financial goals, such as images of a debt-free statement, a dream vacation, or a paid-off home, and review it together monthly to keep motivation high and decisions value-driven
- (For example, use a free online tool to collect images and quotes that symbolize your goals, then set a recurring calendar reminder to look at the board together and discuss progress or adjustments.)
- a practical way to strengthen honest communication is to set up a “financial honesty jar” where each partner anonymously submits notes about any financial worries, confessions, or questions during the week, then read and discuss them together during your regular money check-in
- (For example, if you feel anxious about a recent purchase or unsure about a budget category, write it down and drop it in the jar, ensuring both partners have a safe space to raise concerns without confrontation.)
- you can des ...
Get access to the context and additional materials
Accountability: Jeff's Evaluation Commitment and Both Partners' Cycle-Breaking Commitment
Jeff to See Doctor For ADHD and Other Issues to Aid Family's Financial Recovery
Jeff agrees to seek a medical evaluation to address longstanding behavioral patterns that impact both his mental health and the family's financial well-being. He commits to talking with a doctor about possible ADHD and any related concerns, reaffirming his readiness to listen to professional recommendations after years of resistance. Jeff acknowledges his tendency toward reflexive disagreements—a pattern learned from his drill sergeant father—and recognizes the need for professional support and self-awareness to change this ingrained behavior.
For years, Jeff avoided doctors despite Michelle's encouragement. He confesses discomfort with medical appointments but emphasizes newfound effort, explaining that recently he has made significant steps outside his comfort zone. This includes returning to school, applying for new positions despite a deep-seated dislike for uncertainty, and a conscious attempt to shoulder more responsibility rather than leaving Michelle to carry the burden alone. Personal accountability is crucial, as Michelle has endured the consequences of Jeff’s untreated ADHD and impulsive spending for two decades. Jeff’s willingness to pursue evaluation represents a concrete effort to initiate change for the benefit of their partnership and financial future.
Partners Commit to Break Financial Trauma Cycles and Model Healthy Money Behavior For Children
Both Jeff and Michelle recognize patterns of secrecy and poor financial communication inherited from their parents and commit to breaking these cycles. Michelle strongly opposes her parents' practice of hiding financial struggles and simply telling her "no" without explanation. Instead, she pledges transparency with their children, openly discussing costs and budgeting decisions. When their son asks about expenses or savings, Michelle now answers candidly, sharing information and preparing him for future financial independence, in contrast to the lack of guidance she received.
Jeff also commits to a more open approach, supporting discussions about debt management, savings, and planning for the future. Together, the couple agrees to openly involve their children in conversations about ...
Here’s what you’ll find in our full summary
Accountability: Jeff's Evaluation Commitment and Both Partners' Cycle-Breaking Commitment
Additional Materials
Clarifications
- ADHD (Attention-Deficit/Hyperactivity Disorder) is a neurodevelopmental condition characterized by inattention, impulsivity, and difficulty with organization. These symptoms can lead to challenges in managing money, such as impulsive spending and trouble planning or sticking to budgets. People with ADHD may struggle with financial decisions due to distractibility and difficulty delaying gratification. Proper diagnosis and treatment can improve self-control and financial management skills.
- "Reflexive disagreements" refers to a habitual, automatic response of opposing or arguing without thoughtful consideration. Jeff's drill sergeant father likely modeled strict, confrontational communication, teaching Jeff to react defensively or combatively. This upbringing ingrained a pattern where Jeff instinctively disputes others, hindering open dialogue. Recognizing this helps Jeff understand the need for change to improve relationships and cooperation.
- Financial trauma cycles refer to patterns of emotional stress and harmful behaviors related to money that are passed down through generations. These can include secrecy about finances, fear of discussing money, poor budgeting habits, and mistrust of financial institutions. Such cycles often stem from parents' own negative experiences, like debt, fraud, or financial instability, which shape how they manage and communicate about money. Breaking these cycles involves consciously changing attitudes and behaviors to create healthier financial habits for future generations.
- Secrecy and poor financial communication create mistrust and anxiety within families. They prevent members from understanding the true financial situation, leading to poor decision-making. This lack of openness can cause conflicts and feelings of exclusion or helplessness. Over time, it undermines healthy financial habits and emotional security.
- Fraud involving forged signatures means someone illegally signs another person's name to commit financial crimes. Unauthorized credit occurs when credit accounts are opened without the person's permission, leading to debt and damaged credit scores. These actions can cause long-term financial harm, including difficulty obtaining loans or housing. Victims often face time-consuming disputes and legal challenges to restore their financial reputation.
- Transparency in financial discussions with children helps build their understanding of money management from an early age. It fosters trust and reduces anxiety about money by making financial realities clear. Open conversations teach children practical skills like budgeting and saving, preparing them for responsible adulthood. This approach also breaks harmful secrecy patterns that can lead to financial mistakes or misunderstandings later in life.
- Seeking a medical evaluation involves consulting a healthcare professional who assesses symptoms through interviews, questionnaires, and sometimes tests. This process helps identify conditions like ADHD, which can affect focus, impulsivity, and behavior. Early diagnosis allows for tailored treatment plans, including therapy, medication, or lifestyle changes, improving daily functioning. Ultimately, it ...
Counterarguments
- While seeking a medical evaluation for ADHD and related concerns is a positive step, it is not guaranteed to resolve longstanding behavioral or financial issues without sustained follow-through and additional support.
- Increased transparency with children about finances can be beneficial, but there is a risk of oversharing or causing unnecessary anxiety if not age-appropriate or carefully managed.
- Breaking inherited financial patterns is challenging and may require more than intention and open communication; professional financial counseling or therapy could be necessary for lasting change.
- Personal accountability is important, but systemic factors such as employment opportunities, healthcare access, and broader economic ...
Get access to the context and additional materials

 1-Page Summary
- Couple's Dire Finances: Living Paycheck-To-paycheck on $178k Income
- Unhealthy Relationship: Michelle's Control and Jeff's Avoidance
- Psychological Roots: Childhood Trauma, ADHD, and Money Behavior
- Creating Change: Shared Money Philosophy, Rules, & Weekly Communication
- Accountability: Jeff's Evaluation Commitment and Both Partners' Cycle-Breaking Commitment
Create Summaries for anything on the web
Download the Shortform Chrome extension for your browser